When it comes to determining if a business is eligible to claim a net operating loss (NOL), it depends on the financial situation. If a business’ taxable income is less than its allowable deductions in a set tax period, usually a year, then the business can utilize the NOL deduction on future tax obligations. Since some businesses’ profits and losses result from uneven cycles, the Internal Revenue Service (IRS) Code permits businesses to find a balance with their tax obligations.
How a Net Operating Loss Works
Here is an example showing a business’ situation with annual profit/loss summaries:
Year one: High profits and big tax payments due
Year two: Net operating loss incurred
Year three: High profits and big tax payments due
The way a NOL deduction works in the example above is that the losses from year two can be used to offset taxes due in year three.
Net Operating Loss (NOL) = Taxable Income – Allowable Tax Deductions
Referring to the income statement, if the company’s bottom line is a net loss, then the company might be eligible to take advantage of the NOL deduction.
It’s important to keep in mind there have been modifications to what and how businesses may use this. Until recently, the IRS let businesses utilize the carryback method to offset losses to prior years’ tax bills (up to 24 months of tax liabilities), resulting in an immediate refund. However, with the passage of the Tax Cuts and Jobs Act, NOLs were modified. Effective Jan. 1, 2018, or later, the two-year carryback provision was removed (except for select farming losses), but allowed for an indefinite carryforward period. The TCJA also limits carryforwards to 80 percent of each subsequent year’s net income. Additionally, if a business records a net operating loss in more than one tax year, they must be exhausted in the order that the losses occurred.
The Coronavirus Aid, Relief and Economic Security (CARES) Act permitted NOLs occurring in tax years 2018, 2019, and 2020 to be carried back five years and carried forward indefinitely. However, the exemptions have now expired. Losses that occurred in pre-2018 tax years are still subject to former tax rules, with any remaining losses expiring after 20 years. Beginning with the 2021 tax year, when the Tax Cuts and Jobs Act (TCJA) passed in 2017, it permitted carryforwards of NOLS indefinitely. However, only 80 percent of taxable income can be “carried forward” during a single tax period.
2021 and Forward NOL Example
Year one: NOL $10 million
Year two: Taxable income of $3 million
Year three: Taxable income of $5 million
For year two, with the taxable income’s carryover limit (80 percent) of $3 million is $2.4 million. With the carryover limit subtracted ($3 million – $2.4 million = $600,000), the company’s taxable income will be $600,000 for year two. The remaining NOL of $7.6 million will be considered a “deferred tax asset.” Looking at year three, 80 percent of the year’s $5 million in taxable income equals $4,000,000 in a carryover limit. Subtracting $4 million from $5 million in year three’s taxable income, the business will have $1 million in taxable income, and $3.6 million will be the remaining NOL balance at the end of year three.
With the tax code continuing to evolve, businesses that stay up-to-date with changes in the IRS Code will make the most of their ability to maximize deductions and reduce liabilities.
Evaluating Net Operating Loss Considerations
September 1, 2023 · Accounting News, Blog
⏱ 3 min read
When it comes to determining if a business is eligible to claim a net operating loss (NOL), it depends on the financial situation. If a business’ taxable income is less than its allowable deductions in a set tax period, usually a year, then the business can utilize the NOL deduction on future tax obligations. Since some businesses’ profits and losses result from uneven cycles, the Internal Revenue Service (IRS) Code permits businesses to find a balance with their tax obligations.
How a Net Operating Loss Works
Here is an example showing a business’ situation with annual profit/loss summaries:
Year one: High profits and big tax payments due
Year two: Net operating loss incurred
Year three: High profits and big tax payments due
The way a NOL deduction works in the example above is that the losses from year two can be used to offset taxes due in year three.
Net Operating Loss (NOL) = Taxable Income – Allowable Tax Deductions
Referring to the income statement, if the company’s bottom line is a net loss, then the company might be eligible to take advantage of the NOL deduction.
It’s important to keep in mind there have been modifications to what and how businesses may use this. Until recently, the IRS let businesses utilize the carryback method to offset losses to prior years’ tax bills (up to 24 months of tax liabilities), resulting in an immediate refund. However, with the passage of the Tax Cuts and Jobs Act, NOLs were modified. Effective Jan. 1, 2018, or later, the two-year carryback provision was removed (except for select farming losses), but allowed for an indefinite carryforward period. The TCJA also limits carryforwards to 80 percent of each subsequent year’s net income. Additionally, if a business records a net operating loss in more than one tax year, they must be exhausted in the order that the losses occurred.
The Coronavirus Aid, Relief and Economic Security (CARES) Act permitted NOLs occurring in tax years 2018, 2019, and 2020 to be carried back five years and carried forward indefinitely. However, the exemptions have now expired. Losses that occurred in pre-2018 tax years are still subject to former tax rules, with any remaining losses expiring after 20 years. Beginning with the 2021 tax year, when the Tax Cuts and Jobs Act (TCJA) passed in 2017, it permitted carryforwards of NOLS indefinitely. However, only 80 percent of taxable income can be “carried forward” during a single tax period.
2021 and Forward NOL Example
Year one: NOL $10 million
Year two: Taxable income of $3 million
Year three: Taxable income of $5 million
For year two, with the taxable income’s carryover limit (80 percent) of $3 million is $2.4 million. With the carryover limit subtracted ($3 million – $2.4 million = $600,000), the company’s taxable income will be $600,000 for year two. The remaining NOL of $7.6 million will be considered a “deferred tax asset.” Looking at year three, 80 percent of the year’s $5 million in taxable income equals $4,000,000 in a carryover limit. Subtracting $4 million from $5 million in year three’s taxable income, the business will have $1 million in taxable income, and $3.6 million will be the remaining NOL balance at the end of year three.
With the tax code continuing to evolve, businesses that stay up-to-date with changes in the IRS Code will make the most of their ability to maximize deductions and reduce liabilities.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
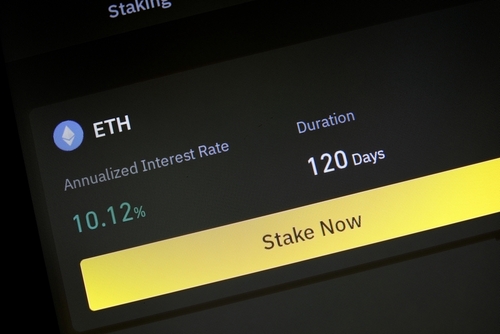
The IRS recently issued an important ruling on the taxability of cryptocurrency staking rewards, determining that staking rewards are essentially “income” and, therefore, taxable upon receipt and not deferrable until sale or swapping. Below, we will look at the ruling in more detail and what it means for taxpayers. But first, let us revisit the concept of cryptocurrency staking as a refresher.
Crypto Staking 101: What Is Staking?
Staking, at its most basic form, is a way for holders of cryptocurrencies to earn rewards or passive income on their digital assets without needing to sell.
One way to think of staking is like a high-yield savings account. When you stake digital assets, you deposit and lock up your coins. This helps run and maintain security on different blockchains (depending on the asset staked). In return, you typically receive more of the digital asset staked.
Rates of return on digital asset staking can be lucrative; however, staking is not without risks.
Staking risks include:
The inherent volatility of cryptocurrencies, where the rewards earned can be less than the change in the underlying digital asset price (causing an overall loss).
Minimum lock-up periods, where staked assets cannot be unstaked and sold or swapped and therefore are illiquid for a period.
Counterparty risk if operating as part of a staking pool, where rewards can be negated as a bad actor and therefore never paid out.
The staking pool or underlying digital asset can be hacked, leading to a loss of funds (remember, there is such a thing as FDIC insurance to protect depositors in the cryptocurrency realm).
Taxability of Staking Rewards
The tax treatment of buying and selling cryptocurrencies is clear. In IRS Notice 2014-21, the government declares that crypto trades should be treated as property, resulting in capital gains treatment like other property bought and sold. Staking, however, is different than trading.
To clarify, given the vague mechanisms of crypto staking, the IRS recently issued a ruling declaring that crypto staking rewards need to be included when received in a taxpayer’s gross income. This ruling formalizes the position taken by the IRS in the Jarrett case.
The argument in the Jarrett case was that the coins received as staking rewards are new property that was created and not the same as income, interest, etc. Essentially, this means the staking rewards are zero-basis assets that would be taxed when sold and not upon receipt. They made the argument that staking rewards were like the products of a baker, where each new cake, although from the same recipe, is a newly created product/asset and, therefore, taxable upon sale.
The court determined that staking rewards, due to their proof-of-stake creation mechanism, are not a new asset, but compensation for helping to maintain and provide validation of the underlying blockchain, with the staked assets used as collateral.
Conclusion
As a result, staking rewards are income when “received.” The taxable amount is the fair market value of the coins when the taxpayer receives the staking reward in an “unlocked” manner. In other words, once the taxpayer controls the staking rewards, the taxpayer is capable (regardless of exercising this capability) of selling them.
IRS Ruling: Crypto Currency Staking Rewards Are Taxable When Received
September 1, 2023 · Blog, Guest Article of the Month
⏱ 3 min read
The IRS recently issued an important ruling on the taxability of cryptocurrency staking rewards, determining that staking rewards are essentially “income” and, therefore, taxable upon receipt and not deferrable until sale or swapping. Below, we will look at the ruling in more detail and what it means for taxpayers. But first, let us revisit the concept of cryptocurrency staking as a refresher.
Crypto Staking 101: What Is Staking?
Staking, at its most basic form, is a way for holders of cryptocurrencies to earn rewards or passive income on their digital assets without needing to sell.
One way to think of staking is like a high-yield savings account. When you stake digital assets, you deposit and lock up your coins. This helps run and maintain security on different blockchains (depending on the asset staked). In return, you typically receive more of the digital asset staked.
Rates of return on digital asset staking can be lucrative; however, staking is not without risks.
Staking risks include:
The inherent volatility of cryptocurrencies, where the rewards earned can be less than the change in the underlying digital asset price (causing an overall loss).
Minimum lock-up periods, where staked assets cannot be unstaked and sold or swapped and therefore are illiquid for a period.
Counterparty risk if operating as part of a staking pool, where rewards can be negated as a bad actor and therefore never paid out.
The staking pool or underlying digital asset can be hacked, leading to a loss of funds (remember, there is such a thing as FDIC insurance to protect depositors in the cryptocurrency realm).
Taxability of Staking Rewards
The tax treatment of buying and selling cryptocurrencies is clear. In IRS Notice 2014-21, the government declares that crypto trades should be treated as property, resulting in capital gains treatment like other property bought and sold. Staking, however, is different than trading.
To clarify, given the vague mechanisms of crypto staking, the IRS recently issued a ruling declaring that crypto staking rewards need to be included when received in a taxpayer’s gross income. This ruling formalizes the position taken by the IRS in the Jarrett case.
The argument in the Jarrett case was that the coins received as staking rewards are new property that was created and not the same as income, interest, etc. Essentially, this means the staking rewards are zero-basis assets that would be taxed when sold and not upon receipt. They made the argument that staking rewards were like the products of a baker, where each new cake, although from the same recipe, is a newly created product/asset and, therefore, taxable upon sale.
The court determined that staking rewards, due to their proof-of-stake creation mechanism, are not a new asset, but compensation for helping to maintain and provide validation of the underlying blockchain, with the staked assets used as collateral.
Conclusion
As a result, staking rewards are income when “received.” The taxable amount is the fair market value of the coins when the taxpayer receives the staking reward in an “unlocked” manner. In other words, once the taxpayer controls the staking rewards, the taxpayer is capable (regardless of exercising this capability) of selling them.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
United States-Taiwan Initiative on 21st-Century Trade First Agreement Implementation Act (HR 4004) – This bipartisan bill was introduced on June 12 by Rep. Jason Smith (R-MO). The purpose of this bill is to convey approval by Congress of the June 1 trade agreement between the United States and Taiwan. The bill addresses customs administration and regulatory practice issues, as well as dictates conditions for negotiations of subsequent trade agreements. Among its provisions, the bill requires that the U.S. Trade Representative share all negotiating texts with Congress prior to being sent to Taiwan or any parties outside of the executive branch. The bill passed in the House on June 21 and in the Senate on July 18. It was signed into law by the President on Aug. 7.
Providing Accountability Through Transparency Act of 2023 (S 111) – This bill, which was signed into law on July 25, requires each agency to provide a 100-word plain language summary of each new proposed rule posted at regulations.gov. The legislation was introduced by Sen. James Lankford (R-OK) on Jan. 26; passed in the Senate on June 22; and in the House on July 17.
Securing the U.S. Organ Procurement and Transplantation Network Act (HR 2544) – This bipartisan bill was introduced by Rep. Larry Bucshon (R-IN) on April 10. It modifies operations of the Organ Procurement and Transplantation Network, which is managed by the Health Resources and Services Administration (HRSA). In the past, the network of professionals was managed by only one organization, but this new bill allows the HRSA to award multiple grants, contracts or cooperative agreements for network management. The legislation was passed in the House on July 25, in the Senate on July 27 and is currently awaiting signature by President Biden.
Strong Communities Act of 2023 (S 994) – Introduced by Sen. Gary Peters (D-MI) on March 28, this bill permits funding by the Community Oriented Policing Services (COPS) grant program to be used to train officers and recruits who agree to serve in law enforcement agencies in their local communities. The bipartisan bill passed in the Senate on July 26 and is currently under consideration in the House.
Recruit and Retain Act (S 546) – Introduced by Sen. Deb Fischer (R-NE) on Feb. 28, this bill expands the Community Oriented Policing Services (COPS) grant program to enable law enforcement agencies to use funding for recruitment activities such as career and job fairs, as well as lower application fees for things like background checks, testing and psychological evaluations. The Act passed in the Senate on July 26 and has been forwarded to the House.
Department of Veterans Affairs Office of Inspector General Training Act of 2023 (S 1096) – This Act would require new Veterans Affairs (VA) employees to undergo training on how to report misconduct, respond to requests from and cooperate with the Office of the Inspector General. The bill was introduced on March 30 by Sen. Margaret Hassan (D-NH) and was passed in the Senate on July 13. Its fate now rests in the House.
Monitoring Trade Agreements with Taiwan, Promoting Plain-Language Rules, and Expanding Recruiting and Training for Law Enforcement
September 1, 2023 · Blog, Congress at Work, News
⏱ 3 min read
United States-Taiwan Initiative on 21st-Century Trade First Agreement Implementation Act (HR 4004) – This bipartisan bill was introduced on June 12 by Rep. Jason Smith (R-MO). The purpose of this bill is to convey approval by Congress of the June 1 trade agreement between the United States and Taiwan. The bill addresses customs administration and regulatory practice issues, as well as dictates conditions for negotiations of subsequent trade agreements. Among its provisions, the bill requires that the U.S. Trade Representative share all negotiating texts with Congress prior to being sent to Taiwan or any parties outside of the executive branch. The bill passed in the House on June 21 and in the Senate on July 18. It was signed into law by the President on Aug. 7.
Providing Accountability Through Transparency Act of 2023 (S 111) – This bill, which was signed into law on July 25, requires each agency to provide a 100-word plain language summary of each new proposed rule posted at regulations.gov. The legislation was introduced by Sen. James Lankford (R-OK) on Jan. 26; passed in the Senate on June 22; and in the House on July 17.
Securing the U.S. Organ Procurement and Transplantation Network Act (HR 2544) – This bipartisan bill was introduced by Rep. Larry Bucshon (R-IN) on April 10. It modifies operations of the Organ Procurement and Transplantation Network, which is managed by the Health Resources and Services Administration (HRSA). In the past, the network of professionals was managed by only one organization, but this new bill allows the HRSA to award multiple grants, contracts or cooperative agreements for network management. The legislation was passed in the House on July 25, in the Senate on July 27 and is currently awaiting signature by President Biden.
Strong Communities Act of 2023 (S 994) – Introduced by Sen. Gary Peters (D-MI) on March 28, this bill permits funding by the Community Oriented Policing Services (COPS) grant program to be used to train officers and recruits who agree to serve in law enforcement agencies in their local communities. The bipartisan bill passed in the Senate on July 26 and is currently under consideration in the House.
Recruit and Retain Act (S 546) – Introduced by Sen. Deb Fischer (R-NE) on Feb. 28, this bill expands the Community Oriented Policing Services (COPS) grant program to enable law enforcement agencies to use funding for recruitment activities such as career and job fairs, as well as lower application fees for things like background checks, testing and psychological evaluations. The Act passed in the Senate on July 26 and has been forwarded to the House.
Department of Veterans Affairs Office of Inspector General Training Act of 2023 (S 1096) – This Act would require new Veterans Affairs (VA) employees to undergo training on how to report misconduct, respond to requests from and cooperate with the Office of the Inspector General. The bill was introduced on March 30 by Sen. Margaret Hassan (D-NH) and was passed in the Senate on July 13. Its fate now rests in the House.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Marketing efforts today depend on collecting, analyzing, and leveraging data to make informed decisions. Therefore, business owners need to understand how to harness the power of data and personalization to create targeted campaigns that drive growth.
Importance of Data and Personalization in Modern Business
Businesses today collect loads of data, enabling them to understand their customers’ preferences, behaviors and interests. The data comes from different channels, such as a business website, emails, or social media. It is then used to identify patterns and trends to make informed marketing decisions. This yields valuable insights that help craft highly personalized and effective marketing strategies.
Data is the foundation of personalization strategies. Personalization involves tailoring customer experiences to meet individual interests, needs, and preferences. It aims to build strong customer relationships, encourage engagement, and drive revenue and growth.
Personalization takes different approaches, such as recommendations based on previous purchases, creating unique landing pages, or sending emails based on customer browsing behavior. For example, e-commerce websites recommend products based on user browsing history and search queries.
Business owners can’t afford to ignore personalization since customers today are more informed, can easily access information, have more options, and have more control over purchase decisions. Furthermore, customers are more demanding and want to be recognized as individuals, expecting to receive personalized experiences. This has rendered traditional, one-size-fits-all marketing strategies obsolete.
How Businesses Can Use Data and Personalization for Targeted Campaigns and Growth
Using a data-driven approach, a business can create campaigns that deliver the right message to the right audience at the right time by doing the following:
1. Audience segmentation
Capturing the attention of a specific audience segment leads to higher conversion rates. To do this, a business can leverage data insights to segment the target audience. This means it is possible to categorize potential customers based on demographics, interests, or browsing behavior.
2. Crafting personalized content
Once segmentation is complete, it becomes possible to create tailored campaigns that resonate with each segment’s unique preferences. Aside from addressing customers by their names, it involves delivering content that speaks directly to their needs, interests, and pain points. This could include product recommendations based on past purchases or sending targeted offers that align with customer browsing history.
3. Omnichannel personalization
Customers interact with businesses using various channels, such as a business website, social media, emails, and mobile apps. A business can integrate data and personalization efforts to ensure a seamless journey for customers, regardless of where they engage. Additionally, it is crucial to deliver consistent and personalized experiences across these channels.
4. Continuous improvement in data-driven campaigns
Data insights also help guide businesses on the most suitable content and distribution strategies. They can analyze types of content performing well and in which channels. For example, a business can conduct A/B testing to compare campaign and content variations to identify the most effective approach for each segment.
5. Measuring and analyzing results
To establish the effectiveness of personalized campaigns, a business will need to develop clear key performance indicators (KPIs) and measurement methods. One way to measure the impact of personalization is through customer engagement. This is done by measures such as click-through rates on personalized emails, customer retention rates, customer lifetime value, customer feedback, and number of sales.
It is worth noting that to make the most out of data insights. It is helpful to invest in advanced analytics tools or collaborate with data experts.
6. Adapting to changing trends
The digital landscape is evolving constantly, with new technologies and trends emerging regularly. Businesses must stay updated on these changes and adapt their personalization strategies accordingly. Remaining flexible and open to innovation ensures that the company’s targeting efforts are relevant and effective.
Data Privacy and Security
Although personalization in modern business is crucial, it must be balanced with privacy concerns. First, a business must be transparent about the data it collects and how it will be used. In addition, businesses need to be careful with the data they collect. They must ensure data security by safeguarding data storage and using safe transmission methods, have access control limits, and regularly audit data privacy policies and practices. Customers should be allowed to opt out of data collection and personalization efforts easily.
Customer data must be well protected to ensure compliance with relevant regulations. It also helps build trust with customers. Besides, a breach of trust can severely affect a business’s reputation and growth.
How Businesses Can Leverage Data and Personalization for Targeted Campaigns and Growth
September 1, 2023 · Blog, News, What's New in Technology
⏱ 4 min read
Marketing efforts today depend on collecting, analyzing, and leveraging data to make informed decisions. Therefore, business owners need to understand how to harness the power of data and personalization to create targeted campaigns that drive growth.
Importance of Data and Personalization in Modern Business
Businesses today collect loads of data, enabling them to understand their customers’ preferences, behaviors and interests. The data comes from different channels, such as a business website, emails, or social media. It is then used to identify patterns and trends to make informed marketing decisions. This yields valuable insights that help craft highly personalized and effective marketing strategies.
Data is the foundation of personalization strategies. Personalization involves tailoring customer experiences to meet individual interests, needs, and preferences. It aims to build strong customer relationships, encourage engagement, and drive revenue and growth.
Personalization takes different approaches, such as recommendations based on previous purchases, creating unique landing pages, or sending emails based on customer browsing behavior. For example, e-commerce websites recommend products based on user browsing history and search queries.
Business owners can’t afford to ignore personalization since customers today are more informed, can easily access information, have more options, and have more control over purchase decisions. Furthermore, customers are more demanding and want to be recognized as individuals, expecting to receive personalized experiences. This has rendered traditional, one-size-fits-all marketing strategies obsolete.
How Businesses Can Use Data and Personalization for Targeted Campaigns and Growth
Using a data-driven approach, a business can create campaigns that deliver the right message to the right audience at the right time by doing the following:
1. Audience segmentation
Capturing the attention of a specific audience segment leads to higher conversion rates. To do this, a business can leverage data insights to segment the target audience. This means it is possible to categorize potential customers based on demographics, interests, or browsing behavior.
2. Crafting personalized content
Once segmentation is complete, it becomes possible to create tailored campaigns that resonate with each segment’s unique preferences. Aside from addressing customers by their names, it involves delivering content that speaks directly to their needs, interests, and pain points. This could include product recommendations based on past purchases or sending targeted offers that align with customer browsing history.
3. Omnichannel personalization
Customers interact with businesses using various channels, such as a business website, social media, emails, and mobile apps. A business can integrate data and personalization efforts to ensure a seamless journey for customers, regardless of where they engage. Additionally, it is crucial to deliver consistent and personalized experiences across these channels.
4. Continuous improvement in data-driven campaigns
Data insights also help guide businesses on the most suitable content and distribution strategies. They can analyze types of content performing well and in which channels. For example, a business can conduct A/B testing to compare campaign and content variations to identify the most effective approach for each segment.
5. Measuring and analyzing results
To establish the effectiveness of personalized campaigns, a business will need to develop clear key performance indicators (KPIs) and measurement methods. One way to measure the impact of personalization is through customer engagement. This is done by measures such as click-through rates on personalized emails, customer retention rates, customer lifetime value, customer feedback, and number of sales.
It is worth noting that to make the most out of data insights. It is helpful to invest in advanced analytics tools or collaborate with data experts.
6. Adapting to changing trends
The digital landscape is evolving constantly, with new technologies and trends emerging regularly. Businesses must stay updated on these changes and adapt their personalization strategies accordingly. Remaining flexible and open to innovation ensures that the company’s targeting efforts are relevant and effective.
Data Privacy and Security
Although personalization in modern business is crucial, it must be balanced with privacy concerns. First, a business must be transparent about the data it collects and how it will be used. In addition, businesses need to be careful with the data they collect. They must ensure data security by safeguarding data storage and using safe transmission methods, have access control limits, and regularly audit data privacy policies and practices. Customers should be allowed to opt out of data collection and personalization efforts easily.
Customer data must be well protected to ensure compliance with relevant regulations. It also helps build trust with customers. Besides, a breach of trust can severely affect a business’s reputation and growth.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
You wake up in the middle of the night. Heart racing, drenched in sweat, and breathing heavily. Thankfully, it was just a nightmare when the IRS showed up at your doorstep unannounced. Recently, however, this was the reality for some taxpayers – and not just a bad dream. The IRS just publicized a significant shift in policy, effectively ending the vast majority of surprise taxpayer visits. The change comes in an effort to create safer conditions for IRS officers as well as ease public concerns.
Who’s Knocking at My Door?
In order to understand the change in policy, you’ll need to understand the three categories of IRS employees that typically interact with taxpayers: Revenue Officers, Revenue Agents, and Special Agents.
IRS Revenue Agents are tax return auditors. They don’t typically show up unannounced.
IRS Revenue Officers, of which there are approximately 2,300, have duties that include paying visits to taxpayers to collect back taxes and tax returns not filed. They are not auditors but instead focus on collection efforts, including issuing liens and levies. Revenue Officers are the main category of IRS employees impacted by the policy change.
Special Agents deal with criminal matters and are part of one of the largest law enforcement agencies in the United States. The change in policy does not impact Special Agents.
Safety
Why the shift to (mostly) eliminating surprise visits from IRS Revenue Officers? Safety is cited as the main concern. Unannounced visits to taxpayers, whether at home or their business, can be risky. Historically, IRS Revenue Officers faced contentious and sometimes dangerous conditions during their unannounced visits.
Taxpayer Confusion
There is also a growing number of scam artists pretending to be IRS agents or officers. As a result, taxpayers are increasingly wary of unannounced visits, and this causes confusion for both the taxpayer and law enforcement.
The difficulty in distinguishing between IRS representatives and fakes has caused concern for taxpayers already on guard for scam artists. The IRS believes that maintaining trust among the public will go a long way to maintaining the legitimacy of the organization.
Appointment Letters In Lieu of Visits
In place of these previously unannounced visits, the IRS will contact taxpayers through a 725-B letter, more colloquially known as an appointment letter.
An appointment letter will facilitate scheduling in-person meetings, with the opportunity for the taxpayer to prepare any information and documentation beforehand, allowing for quicker resolution of cases. These meetings occur at a pre-determined time, date, and place.
Limited Visits Will Still Occur
The policy change does not completely eliminate unannounced visits by the IRS. In “extremely limited situations,” such as serving summonses and subpoenas and the seizure of assets, unannounced visits will still occur. To give some perspective, these types of visits will account for only a few hundred per year compared to the tens of thousands of unannounced visits under the old policy.
Conclusion
Unannounced IRS visits are (almost) a thing of the past. They will be carried out only in rare, necessary cases, with most Revenue Officer visits being pre-scheduled. This should ease taxpayer anxiety and make case resolution more efficient.
IRS Announces End of Unannounced Taxpayer Visits (Mostly)
September 1, 2023 · Blog, Tax and Financial News
⏱ 3 min read
You wake up in the middle of the night. Heart racing, drenched in sweat, and breathing heavily. Thankfully, it was just a nightmare when the IRS showed up at your doorstep unannounced. Recently, however, this was the reality for some taxpayers – and not just a bad dream. The IRS just publicized a significant shift in policy, effectively ending the vast majority of surprise taxpayer visits. The change comes in an effort to create safer conditions for IRS officers as well as ease public concerns.
Who’s Knocking at My Door?
In order to understand the change in policy, you’ll need to understand the three categories of IRS employees that typically interact with taxpayers: Revenue Officers, Revenue Agents, and Special Agents.
IRS Revenue Agents are tax return auditors. They don’t typically show up unannounced.
IRS Revenue Officers, of which there are approximately 2,300, have duties that include paying visits to taxpayers to collect back taxes and tax returns not filed. They are not auditors but instead focus on collection efforts, including issuing liens and levies. Revenue Officers are the main category of IRS employees impacted by the policy change.
Special Agents deal with criminal matters and are part of one of the largest law enforcement agencies in the United States. The change in policy does not impact Special Agents.
Safety
Why the shift to (mostly) eliminating surprise visits from IRS Revenue Officers? Safety is cited as the main concern. Unannounced visits to taxpayers, whether at home or their business, can be risky. Historically, IRS Revenue Officers faced contentious and sometimes dangerous conditions during their unannounced visits.
Taxpayer Confusion
There is also a growing number of scam artists pretending to be IRS agents or officers. As a result, taxpayers are increasingly wary of unannounced visits, and this causes confusion for both the taxpayer and law enforcement.
The difficulty in distinguishing between IRS representatives and fakes has caused concern for taxpayers already on guard for scam artists. The IRS believes that maintaining trust among the public will go a long way to maintaining the legitimacy of the organization.
Appointment Letters In Lieu of Visits
In place of these previously unannounced visits, the IRS will contact taxpayers through a 725-B letter, more colloquially known as an appointment letter.
An appointment letter will facilitate scheduling in-person meetings, with the opportunity for the taxpayer to prepare any information and documentation beforehand, allowing for quicker resolution of cases. These meetings occur at a pre-determined time, date, and place.
Limited Visits Will Still Occur
The policy change does not completely eliminate unannounced visits by the IRS. In “extremely limited situations,” such as serving summonses and subpoenas and the seizure of assets, unannounced visits will still occur. To give some perspective, these types of visits will account for only a few hundred per year compared to the tens of thousands of unannounced visits under the old policy.
Conclusion
Unannounced IRS visits are (almost) a thing of the past. They will be carried out only in rare, necessary cases, with most Revenue Officer visits being pre-scheduled. This should ease taxpayer anxiety and make case resolution more efficient.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
In light of our current economy, making sure your money works hard for you is one of the best things to do this year. Here are some ways you can navigate your financial situation, keep tabs on where you are, and adjust if you need to.
Shop for a higher return on savings. These days, every extra cent counts. That’s why it pays to look around for higher rates on savings accounts. Several places to check out are PNC (4.65 percent APY), Sofi (up to 4.4 percent APY), and American Express (4 percent APY). Here are a few others. Rates may increase even more with the Federal Reserve’s rate hike announcement on July 27.
Open an HSA account. When you have one of these, it will help you pay for expenses that your health insurance plan doesn’t cover. If you’re enrolled in a high-deductible insurance plan, you and possibly your employer can contribute pre-tax dollars into this account, from which you’ll use funds you’ve stocked away for qualified medical expenses. Whatever money you don’t use will roll over to the next year, unlike FSA accounts.
Consolidate debt. Why pay a bunch of different interest rates on all your credit cards? If you have debt, find one card with a very low-interest rate and do a balance transfer. Some credit cards offer 0 percent APR as an introductory rate, which will be a big savings to get a jumpstart on becoming debt-free. Here are a few good ones: Bank of America® Travel Rewards Credit Card now offers 0 percent APR for 18 months. Discover it® Cash Back offers 0 percent APR for 15 months. Find other great deals here.
Cut how much you pay on car insurance. Have you shopped around lately? We know this might seem like a pain, as it takes a lot of time, but here’s some good news, and it’s called The Zebra. This amazing site has done all the heavy lifting for you. Here, you’ll find dozens of real-time comparisons from many trusted companies.
Max out your 401K. This year, the maximum yearly contribution limit has been raised by $200 to $22,500 (up from $20,500 in 2022). Even better, if you’re over 50, you can set aside catch-up contributions of $7,500, allowing a total contribution of up to $30,000. This allowance lets older workers add as much as they can so that when they retire, they’ll be in a better financial situation.
Update your W-4. No one likes a shock when it comes to paying taxes. That’s why this is such a smart idea. And the IRS actually has a tool that can help you: The Tax Withholding Estimator. Go here to find out if your employer is taking enough money out for taxes. If you’re falling short, you’ll know. Better to learn and fix this before it’s too late.
Create a net worth statement. When you have a realistic idea of your assets and liabilities, you’ll be able to see whether or not you’re on the right track with retirement. This way, you’ll be able to set up new goals for yourself if you feel you need to.
Keeping up with your finances, while time-consuming, really pays off. If you try one (or all) of these hacks, you’ll be better off in no time.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
According to the Internal Revenue Service (IRS) and the National Federation of Independent Businesses (NFIB), almost one-third of companies see penalties due to payroll issues. Understanding a few examples, according to the NFIB, of how companies can better comply and avoid penalties is essential to smoother operations.
Underpayment of Estimated Tax by Corporations Penalty
As long as there’s a reasonable expectation of at least $500 in estimated taxes owed, corporations are required by the IRS to file. If, however, a corporation doesn’t satisfy its estimated tax payments or pays them after their quarterly submission deadline, the IRS will assess penalties. This can occur even if the IRS owes filers a refund.
The IRS recommends the easiest way to avoid the penalty is to pay the quarterly estimated taxes by the 15th day of April, June, September, and January of the following year (the following month after each quarter). If the 15th is on a weekend (Saturday or Sunday) or it’s a legal federal holiday, payment would be due on the next regular business day.
When it comes to assessing penalties for underpayment of estimated taxes, the IRS determines the penalty based on how much-estimated taxes are underpaid, the time frame of when the payment was due and underpaid, and the IRS’ current quarterly interest rates.
Based on 2023’s third-quarter data from the IRS, the federal agency charges a 7 percent penalty annually, compounded daily.
Failure to Deposit Penalty
Another payroll tax mistake businesses may make is the Failure to Deposit Penalty. The NFIB reported that nearly 50 percent of small businesses see fines on average of $850 annually because they’re late or missing payments. In order for businesses that must make employment tax deposits, it’s imperative to do so either on the IRS’ monthly or semi-weekly basis.
Required employment tax deposits cover Social Security, Medicare, and federal income taxes, along with Federal Unemployment Tax. Employers on the monthly route are required to deposit employment taxes on payments for the prior month by the 15th of the following month. For the semi-weekly route, deposits for employment taxes on payments made between Wednesdays and Fridays are to be made by the following Wednesday. For deposits done on a Saturday, Sunday, Monday, or Tuesday, employment tax deposits must be made by the following Friday.
Beginning with the due date of the employment tax deposit, the penalty is calculated by the number of calendar days the deposit is late.
Between one and five calendar days, there’s a 2 percent penalty on the unpaid deposit. Between six and 15 calendar days, the penalty increases to 5 percent of the unpaid deposit. If it’s late by more than 15 calendar days, the penalty is 10 percent of the unpaid deposit amount.
If more than 10 calendar days have passed after the first written contact from the IRS notifying the filer of failing to deposit their employment taxes or the day the business receives correspondence requiring immediate payment of employment taxes, the penalty increases to 15 percent of the unpaid deposit. It’s also subject to interest on the penalty.
While these are only two ways businesses can incur payroll-related tax penalties, it’s illustrative of how businesses need to keep on top of their federal (and state) obligations.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
When a company decides to conduct a reverse stock split, also referred to as a stock consolidation, the number of shares available to investors is reduced.
In a normal (forward) stock split, a company increases its number of outstanding shares without changing their market value. For example, one share of stock valued at $200 may split into two shares, with the shares then valued at $100 each. So, with a shareholder who holds 10 shares for a total of value of $2,000, a traditional one-to-two (1:2) stock split would change his holding to 20 shares – still valued at $2,000. The difference is that the value of each stock would change from $200 to $100.
The opposite occurs with a reverse stock split; a company decreases its number of outstanding shares without changing their market value. Using the same example, a shareholder who owns 10 shares at $200 would hold only five shares after a 2:1 reverse stock split. However, the worth of each share would double in value to $400.
Why Conduct a Reverse Stock Split?
A reverse stock split often indicates that a company is in financial distress, its stock price is on a downward spiral and it wants to reverse that momentum by giving investors a higher share value. This makes individual stocks more valuable to sell. In many cases, the company’s sinking stock price puts it in danger of losing its place on a stock exchange, which would then limit the pool of possible buyers – particularly fund managers and stock brokers. In most cases, companies that conduct a reverse stock split are small, lightly traded companies as well as some exchange-traded funds.
Impact on Small, Retail Investors
Smaller investors are more likely to be negatively impacted by a reverse stock split because they are more likely to own fewer numbers or fractional shares. For example, if a company conducts a 20:1 reverse stock split, investors receive only one share for every 20 they hold. However, if a shareholder owns less than 20 shares, he will simply be paid cash for his shares and his position would dissolve. This also holds true if the investor owns an uneven multiple of the reverse split. In the scenario of a 20:1 stock split, if the investor held 110 shares, he would receive five new post-split shares and be paid in cash for the remaining 10 shares.
How Do Stocks Perform After a Reverse Split?
While the total value of a shareholder’s holding would not change after a reverse stock split, history has shown that share prices after a reverse split tend to stagnate or continue to drop. After all, the company was likely already in financial distress, and this action serves to increase the price of a failing stock. It does not usually entice new investors or motivate current ones to invest more money in the company.
Potential Advantages and Disadvantages of Reverse Splits
To remain listed on a major stock exchange such as the NYSE or Nasdaq, a company’s share price must trade at $5 or higher. The advantage of a reverse stock split is that it increases the value of shares, which may allow them to remain listed on a major exchange. This offers value to both the investor and the company, as exchanges attract far more investors whose interest can help drive up the stock price.
Another scenario in which a reverse stock split is advantageous is if a corporation is planning to spin off a portion of its business into a separate company. By conducting a reverse stock split before the spinoff, shares of the new company are assured of having a high enough stock price to be listed on a major stock exchange.
However, a reverse stock split is most often a signal that the company is failing, is worried about a pervasive decline in its stock price, and is seeking a way to artificially increase investor share prices.
The Ins and Outs of a Reverse Stock Split
August 1, 2023 · Blog, Financial Planning, News
⏱ 4 min read
When a company decides to conduct a reverse stock split, also referred to as a stock consolidation, the number of shares available to investors is reduced.
In a normal (forward) stock split, a company increases its number of outstanding shares without changing their market value. For example, one share of stock valued at $200 may split into two shares, with the shares then valued at $100 each. So, with a shareholder who holds 10 shares for a total of value of $2,000, a traditional one-to-two (1:2) stock split would change his holding to 20 shares – still valued at $2,000. The difference is that the value of each stock would change from $200 to $100.
The opposite occurs with a reverse stock split; a company decreases its number of outstanding shares without changing their market value. Using the same example, a shareholder who owns 10 shares at $200 would hold only five shares after a 2:1 reverse stock split. However, the worth of each share would double in value to $400.
Why Conduct a Reverse Stock Split?
A reverse stock split often indicates that a company is in financial distress, its stock price is on a downward spiral and it wants to reverse that momentum by giving investors a higher share value. This makes individual stocks more valuable to sell. In many cases, the company’s sinking stock price puts it in danger of losing its place on a stock exchange, which would then limit the pool of possible buyers – particularly fund managers and stock brokers. In most cases, companies that conduct a reverse stock split are small, lightly traded companies as well as some exchange-traded funds.
Impact on Small, Retail Investors
Smaller investors are more likely to be negatively impacted by a reverse stock split because they are more likely to own fewer numbers or fractional shares. For example, if a company conducts a 20:1 reverse stock split, investors receive only one share for every 20 they hold. However, if a shareholder owns less than 20 shares, he will simply be paid cash for his shares and his position would dissolve. This also holds true if the investor owns an uneven multiple of the reverse split. In the scenario of a 20:1 stock split, if the investor held 110 shares, he would receive five new post-split shares and be paid in cash for the remaining 10 shares.
How Do Stocks Perform After a Reverse Split?
While the total value of a shareholder’s holding would not change after a reverse stock split, history has shown that share prices after a reverse split tend to stagnate or continue to drop. After all, the company was likely already in financial distress, and this action serves to increase the price of a failing stock. It does not usually entice new investors or motivate current ones to invest more money in the company.
Potential Advantages and Disadvantages of Reverse Splits
To remain listed on a major stock exchange such as the NYSE or Nasdaq, a company’s share price must trade at $5 or higher. The advantage of a reverse stock split is that it increases the value of shares, which may allow them to remain listed on a major exchange. This offers value to both the investor and the company, as exchanges attract far more investors whose interest can help drive up the stock price.
Another scenario in which a reverse stock split is advantageous is if a corporation is planning to spin off a portion of its business into a separate company. By conducting a reverse stock split before the spinoff, shares of the new company are assured of having a high enough stock price to be listed on a major stock exchange.
However, a reverse stock split is most often a signal that the company is failing, is worried about a pervasive decline in its stock price, and is seeking a way to artificially increase investor share prices.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
When it comes to accounting for capital assets, specifically depreciating capital assets, the Governmental Accounting Standards Board (GASB) provides guidance to state and local governments for accounting processes. The GASB is responsible for the generally accepted accounting principles (GAAP) for the private sector (corporate and business accounting), and it works to promote clear, consistent, transparent, and comparable financial reporting.
One of the three primary GASB pronouncements that impact how these agencies manage their fixed assets includes Statement No. 34, which requires all government entities to use accrual accounting. In addition, such entities must depreciate their capital assets according to its guidelines.
Under the section titled “Basic Financial Statements and Management’s Discussion and Analysis for State and Local Governments,” Statement No. 34 mandates when entities must comply depending on the entity’s annual revenues. Entities with $100 million plus must comply beginning with their first fiscal year after June 15, 2001. Entities with annual revenues of between $10 million and $100 million must comply starting with their first fiscal year post-June 15, 2002. Entities with annual revenues of up to $10 million must comply by their first fiscal year after June 15, 2003.
Capital Assets Overview
The first step in determining a capital asset is to ensure it has a useful life greater than a single reporting period. Examples of capital assets include vehicles, easements, buildings, land and land improvements, and infrastructure (tunnels, bridges, roads, lighting systems, etc.). When defining infrastructure, it must be something that can be used for the long term; generally is stationary, and when a building is looked at, it’s included only if the building is integral to a network of infrastructure assets.
When it comes to reporting capital assets, they should be reported at their historical costs (inclusive of installation and freight charges). For donated assets, they should be recorded at their fair market value at time received.
Depreciation Expense Reporting Considerations
When an asset is identified with a specific function, it’s recommended to be a direct expense. This includes appropriate assets that are attributable to a unique department or role. If the asset is used by many different departments and there are depreciation expenses, they should be proportionate to how each department uses the respective assets. Additionally, if an asset function across multiple departments or across citywide functions, its depreciation expense is not categorized as a direct expense but rather as a separate line in the Statement of Activities.
Whether it’s straight or declining balance methods (such as double declining balance and 150 percent declining balance), it is done over the asset’s useful life. When it comes to determining an asset’s useful life, government entities can base their calculations on their own past internal experience for similar needs, how other government entities treated similar asset classifications that are publicly available, or industry or professional organization’s published guidelines. Condition and the expected service life are two important factors to be considered.
Another important factor in how depreciation is calculated depends on how assets themselves are classified. For example, it can be done through the following lenses:
Individual assets
Classes of assets
Networks of assets
Subsystems of a network of assets
Looking at the last two ways to analyze these assets for depreciation, rural roads, state highways, and Interstate highways can be broken down into three discrete systems, also referred to as a subsystem of the network. However, if all three different transportation systems are grouped together, the bigger system would be a network of infrastructure assets or a network of assets.
With capital assets expected to be a part of governments’ budgets, understanding the intricacies is essential to ensure standards are met.
How to Account for Capital Assets
August 1, 2023 · Accounting News, Blog
⏱ 4 min read
When it comes to accounting for capital assets, specifically depreciating capital assets, the Governmental Accounting Standards Board (GASB) provides guidance to state and local governments for accounting processes. The GASB is responsible for the generally accepted accounting principles (GAAP) for the private sector (corporate and business accounting), and it works to promote clear, consistent, transparent, and comparable financial reporting.
One of the three primary GASB pronouncements that impact how these agencies manage their fixed assets includes Statement No. 34, which requires all government entities to use accrual accounting. In addition, such entities must depreciate their capital assets according to its guidelines.
Under the section titled “Basic Financial Statements and Management’s Discussion and Analysis for State and Local Governments,” Statement No. 34 mandates when entities must comply depending on the entity’s annual revenues. Entities with $100 million plus must comply beginning with their first fiscal year after June 15, 2001. Entities with annual revenues of between $10 million and $100 million must comply starting with their first fiscal year post-June 15, 2002. Entities with annual revenues of up to $10 million must comply by their first fiscal year after June 15, 2003.
Capital Assets Overview
The first step in determining a capital asset is to ensure it has a useful life greater than a single reporting period. Examples of capital assets include vehicles, easements, buildings, land and land improvements, and infrastructure (tunnels, bridges, roads, lighting systems, etc.). When defining infrastructure, it must be something that can be used for the long term; generally is stationary, and when a building is looked at, it’s included only if the building is integral to a network of infrastructure assets.
When it comes to reporting capital assets, they should be reported at their historical costs (inclusive of installation and freight charges). For donated assets, they should be recorded at their fair market value at time received.
Depreciation Expense Reporting Considerations
When an asset is identified with a specific function, it’s recommended to be a direct expense. This includes appropriate assets that are attributable to a unique department or role. If the asset is used by many different departments and there are depreciation expenses, they should be proportionate to how each department uses the respective assets. Additionally, if an asset function across multiple departments or across citywide functions, its depreciation expense is not categorized as a direct expense but rather as a separate line in the Statement of Activities.
Whether it’s straight or declining balance methods (such as double declining balance and 150 percent declining balance), it is done over the asset’s useful life. When it comes to determining an asset’s useful life, government entities can base their calculations on their own past internal experience for similar needs, how other government entities treated similar asset classifications that are publicly available, or industry or professional organization’s published guidelines. Condition and the expected service life are two important factors to be considered.
Another important factor in how depreciation is calculated depends on how assets themselves are classified. For example, it can be done through the following lenses:
Individual assets
Classes of assets
Networks of assets
Subsystems of a network of assets
Looking at the last two ways to analyze these assets for depreciation, rural roads, state highways, and Interstate highways can be broken down into three discrete systems, also referred to as a subsystem of the network. However, if all three different transportation systems are grouped together, the bigger system would be a network of infrastructure assets or a network of assets.
With capital assets expected to be a part of governments’ budgets, understanding the intricacies is essential to ensure standards are met.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
CADETS Act (S 467) – This bipartisan bill was introduced on Feb. 16 by Sen. Gary Peters (D-MI). The purpose of this bipartisan bill is to change the age requirements (previously limited to age 25 and younger) for the Student Incentive Payment Program. This program provides financial support to cadets of state maritime academies who enlist or commission in the Navy Reserve at the time of their graduation. The bill passed in the Senate on March 29 and in the House on June 14. It was enacted on June 30.
Veterans’ Compensation Cost-of-Living Adjustment Act of 2023 (S 777) – This bipartisan bill, which was signed into law on June 14, requires the Department of Veterans Affairs to increase the amount of wartime disability compensation by the same percentage as the cost-of-living increase benefits for Social Security recipients, effective on Dec. 1, 2023. The bill also authorizes a similar adjustment to compensation for people who have not received compensation for a service-connected disability or death. The bipartisan bill was introduced by Sen. Jon Tester (D-MT) on March 14.
Fiscal Year 2023 Veterans Affairs Major Medical Facility Authorization Act (S 30) – This Act authorizes the development of and funding for major medical facility projects by Department of Veterans Affairs during this fiscal year. The bill was introduced by Sen. Jon Tester (D-MT) on Jan. 24. The legislation was passed in the Senate on March 21, in the House on June 20, and was signed into law by President Biden on July 18.
Modification to Department of Defense Travel Authorities for Abortion-Related Expenses Act of 2023 (S 822) – Introduced by Sen. Joni Ernst (R-IA) on March 15, this bill would reverse the Pentagon’s new policy of paying for travel if a military service member goes outofstate for access to reproductive health care. The new rule was in response to recent state laws that functionally banned abortion in locations where military bases are located. Support for the Act is generally split among partisan lines, with Republicans advocating and Democrats opposing. A similar bill has been introduced in the House. The Senate bill is currently under committee review.
Disclosing Foreign Influence in Lobbying Act (S 829) – This bill was introduced in the House by Sen. Chuck Grassley (R-IA) on March 16. It mandates that registered lobbyists must disclose their relationship with any foreign countries or political parties involved in the direction, planning, supervision or control of the lobbyist’s activities. This bipartisan bill (co-sponsored by four Democrats, two Republicans and one Independent) passed in the Senate on June 22. It has been forwarded to the House for consideration.
Supreme Court Ethics, Recusal and Transparency Act of 2023 (S 359) – This Act is designed to strengthen the code of ethics to restrain inappropriate activities of U.S. Supreme Court Justices. Provisions of the bill include expanding circumstances under which a judge must be disqualified; adopting rules for the disclosure of gifts, travel and income received by the justices and law clerks; and establishing procedures to receive and investigate complaints of judicial misconduct. The bill was introduced on Feb. 9 by Sen. Sheldon Whitehouse (D-RI) and is awaiting a formal report out of committee.
AI Disclosure Act of 2023 (HR 3831) – This legislation, introduced on June 5 by Rep. Ritchie Torres (D-NY), would require that any content produced by AI (which includes ChatGPT) be accompanied by a disclaimer that reads: “This output has been generated by artificial intelligence.” The bill has yet to be assigned to committee for review.
Compensating Service Members and Establishing Rules and Procedures for Ethical Matters
August 1, 2023 · Blog, Congress at Work, News
⏱ 3 min read
CADETS Act (S 467) – This bipartisan bill was introduced on Feb. 16 by Sen. Gary Peters (D-MI). The purpose of this bipartisan bill is to change the age requirements (previously limited to age 25 and younger) for the Student Incentive Payment Program. This program provides financial support to cadets of state maritime academies who enlist or commission in the Navy Reserve at the time of their graduation. The bill passed in the Senate on March 29 and in the House on June 14. It was enacted on June 30.
Veterans’ Compensation Cost-of-Living Adjustment Act of 2023 (S 777) – This bipartisan bill, which was signed into law on June 14, requires the Department of Veterans Affairs to increase the amount of wartime disability compensation by the same percentage as the cost-of-living increase benefits for Social Security recipients, effective on Dec. 1, 2023. The bill also authorizes a similar adjustment to compensation for people who have not received compensation for a service-connected disability or death. The bipartisan bill was introduced by Sen. Jon Tester (D-MT) on March 14.
Fiscal Year 2023 Veterans Affairs Major Medical Facility Authorization Act (S 30) – This Act authorizes the development of and funding for major medical facility projects by Department of Veterans Affairs during this fiscal year. The bill was introduced by Sen. Jon Tester (D-MT) on Jan. 24. The legislation was passed in the Senate on March 21, in the House on June 20, and was signed into law by President Biden on July 18.
Modification to Department of Defense Travel Authorities for Abortion-Related Expenses Act of 2023 (S 822) – Introduced by Sen. Joni Ernst (R-IA) on March 15, this bill would reverse the Pentagon’s new policy of paying for travel if a military service member goes outofstate for access to reproductive health care. The new rule was in response to recent state laws that functionally banned abortion in locations where military bases are located. Support for the Act is generally split among partisan lines, with Republicans advocating and Democrats opposing. A similar bill has been introduced in the House. The Senate bill is currently under committee review.
Disclosing Foreign Influence in Lobbying Act (S 829) – This bill was introduced in the House by Sen. Chuck Grassley (R-IA) on March 16. It mandates that registered lobbyists must disclose their relationship with any foreign countries or political parties involved in the direction, planning, supervision or control of the lobbyist’s activities. This bipartisan bill (co-sponsored by four Democrats, two Republicans and one Independent) passed in the Senate on June 22. It has been forwarded to the House for consideration.
Supreme Court Ethics, Recusal and Transparency Act of 2023 (S 359) – This Act is designed to strengthen the code of ethics to restrain inappropriate activities of U.S. Supreme Court Justices. Provisions of the bill include expanding circumstances under which a judge must be disqualified; adopting rules for the disclosure of gifts, travel and income received by the justices and law clerks; and establishing procedures to receive and investigate complaints of judicial misconduct. The bill was introduced on Feb. 9 by Sen. Sheldon Whitehouse (D-RI) and is awaiting a formal report out of committee.
AI Disclosure Act of 2023 (HR 3831) – This legislation, introduced on June 5 by Rep. Ritchie Torres (D-NY), would require that any content produced by AI (which includes ChatGPT) be accompanied by a disclaimer that reads: “This output has been generated by artificial intelligence.” The bill has yet to be assigned to committee for review.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
 When it comes to determining if a business is eligible to claim a net operating loss (NOL), it depends on the financial situation. If a business’ taxable income is less than its allowable deductions in a set tax period, usually a year, then the business can utilize the NOL deduction on future tax obligations. Since some businesses’ profits and losses result from uneven cycles, the Internal Revenue Service (IRS) Code permits businesses to find a balance with their tax obligations.



 The IRS recently issued an important ruling on the taxability of cryptocurrency staking rewards, determining that staking rewards are essentially “income” and, therefore, taxable upon receipt and not deferrable until sale or swapping. Below, we will look at the ruling in more detail and what it means for taxpayers. But first, let us revisit the concept of cryptocurrency staking as a refresher.
 United States-Taiwan Initiative on 21st-Century Trade First Agreement Implementation Act (HR 4004) – This bipartisan bill was introduced on June 12 by Rep. Jason Smith (R-MO). The purpose of this bill is to convey approval by Congress of the June 1 trade agreement between the United States and Taiwan. The bill addresses customs administration and regulatory practice issues, as well as dictates conditions for negotiations of subsequent trade agreements. Among its provisions, the bill requires that the U.S. Trade Representative share all negotiating texts with Congress prior to being sent to Taiwan or any parties outside of the executive branch. The bill passed in the House on June 21 and in the Senate on July 18. It was signed into law by the President on Aug. 7.
 Marketing efforts today depend on collecting,
 You wake up in the middle of the night. Heart racing, drenched in sweat, and breathing heavily. Thankfully, it was just a nightmare when the IRS showed up at your doorstep unannounced. Recently, however, this was the reality for some taxpayers – and not just a bad dream. The IRS just publicized a significant shift in policy, effectively ending the vast majority of surprise taxpayer visits. The change comes in an effort to create safer conditions for IRS officers as well as ease public concerns.
 In light of our current economy, making sure your money works hard for you is one of the best things to do this year. Here are some ways you can navigate your financial situation, keep tabs on where you are, and adjust if you need to.
 According to the Internal Revenue Service (IRS) and the National Federation of Independent Businesses (NFIB), almost one-third of companies see penalties due to payroll issues. Understanding a few examples, according to the NFIB, of how companies can better comply and avoid penalties is essential to smoother operations.
 When a company decides to conduct a reverse stock split, also referred to as a stock consolidation, the number of shares available to investors is reduced.
 When it comes to accounting for capital assets, specifically depreciating capital assets, the Governmental Accounting Standards Board (GASB) provides guidance to state and local governments for accounting processes. The GASB is responsible for the generally accepted accounting principles (GAAP) for the private sector (corporate and business accounting), and it works to promote clear, consistent, transparent, and comparable financial reporting.
 CADETS Act (S 467) – This bipartisan bill was introduced on Feb. 16 by Sen. Gary Peters (D-MI). The purpose of this bipartisan bill is to change the age requirements (previously limited to age 25 and younger) for the Student Incentive Payment Program. This program provides financial support to cadets of state maritime academies who enlist or commission in the Navy Reserve at the time of their graduation. The bill passed in the Senate on March 29 and in the House on June 14. It was enacted on June 30.