Whether you file your income tax return early or at the last minute, there are ways to simplify the process and reduce what you owe – or even increase your refund – before the deadline.
Filing Simplification Tip
Once you receive your W-2 and/or 1099 tax forms, see what income tax bracket you fall under to determine whether you should itemize expenses or take the standard deduction. Thinking about this step first can save you a lot of time. If you don’t come near the standard deduction amount, you will not be itemizing expenses. And if you are not itemizing expenses, you won’t have to gather all the receipts (e.g., mortgage interest, property tax, state and local income taxes, and sales tax paid in 2024).
2024 Tax Season Income Tax Brackets
Single filer
Married filing separately
Married filing jointly (includes qualifying widow/er)
Head of Household
Tax Rate
$0 to $11,600
$0 to $11,600
$0 to $23,200
$0 to $16,550
10%
$11,601 to $47,150
$11,601 to $47,150
$23,201 to $94,300
$16,551 to $63,100
12%
$47,151 to $100,525
$47,151 to $100,525
$94,301 to $201,050
$63,101 to $100,500
22%
$100,526 to $191,950
$100,526 to $191,950
$201,051 to $383,900
$100,501 to $191,950
24%
$191,951 to $243,725
$191,951 to $243,725
$383,901 to $487,450
$191,951 to $243,700
32%
$243,726 to $609,350
$243,726 to $365,600
$487,451 to $731,200
$243,701 to $609,350
35%
$609,351 or more
$365,601 or more
$731,201 or more
$609,351 or more
37%
2024 Tax Season Standard Deductions
Single filer and married filing separately
Married filing jointly (includes qualifying widow/er)
Head of Household
$14,600
$29,200
$21,900
Retirement Saving Tips
It’s not too late to contribute to an IRA. Both the traditional and Roth IRAs allow you to make contributions for 2024 up until the tax-filing deadline of the following year – which this year is Tuesday, April 15. The advantage to this later deadline is that you can complete your taxes before they are due, then adjust them to reduce your tax liability if needed by contributing to your IRA. The total maximum contribution you can make to all of your IRAs combined (both Roths and traditional) is $7,000 for 2024 or $8,000 if you are 50 years or older.
However, if you have a Roth IRA, there are restrictions to contributions based on your 2024 income. You may make the maximum contribution to your Roth only if your 2024 modified adjusted gross income (MAGI) is less than a certain threshold.
Filing Status
MAGI
Contribution amount
Single and Head of Household filers
Below $146,000
Between $146,001 and 161,000
Above $161,000
$7,000/$8,000 (age 50+)
Phased (IRS Worksheet 2-2)
Nothing
Married filing jointly
(includes qualifying widow/er)
Below $230,000
Between $230,000 and $240,000
Above $240,000
$7,000/$8,000 (age 50+)
Phased (IRS Worksheet 2-2)
Nothing
Be aware that the amount of deduction you can claim for a traditional IRA contribution may be limited if you or your spouse are covered by a retirement plan at work.
Filing Status
MAGI
Deduction amount
Single and Head of Household filers
$77,000 or less
Between $77,000 and 87,000
$87,000 or more
Full deduction
Partial (IRS Worksheet 1-2)
None
Married filing jointly
(includes qualifying widow/er)
$123,000 or less
Between $123,000 and 143,000
$143,000 or more
Full deduction
Partial (IRS Worksheet 1-2)
None
Married filing separately
Less than $10,000
$10,000 or more
Partial (IRS Worksheet 1-2)
None
If you make a traditional and/or Roth IRA contribution by the April 15 deadline, you may qualify for the Retirement Saver’s Credit (also available if you contributed to an employer plan by Dec. 31, 2024). The maximum credit is $1,000 ($2,000 for married couples), and it can increase your refund or reduce the tax you owe. However, the saver’s credit is subject to other deductions, credits, and income restrictions.
Filing Status
MAGI
Single and Married filing separately
up to $57,375
Married couples filing jointly
(includes qualifying widow/er)
up to $76,500
Head of Household Filers
up to $57,375
Work with an experienced tax preparer to take advantage of legitimate deductions and credits to ensure that you only pay what is required for your situation.
Tips for Tax Season
January 1, 2025 · Blog, Financial Planning, News
⏱ 4 min read
Whether you file your income tax return early or at the last minute, there are ways to simplify the process and reduce what you owe – or even increase your refund – before the deadline.
Filing Simplification Tip
Once you receive your W-2 and/or 1099 tax forms, see what income tax bracket you fall under to determine whether you should itemize expenses or take the standard deduction. Thinking about this step first can save you a lot of time. If you don’t come near the standard deduction amount, you will not be itemizing expenses. And if you are not itemizing expenses, you won’t have to gather all the receipts (e.g., mortgage interest, property tax, state and local income taxes, and sales tax paid in 2024).
2024 Tax Season Income Tax Brackets
Single filer
Married filing separately
Married filing jointly (includes qualifying widow/er)
Head of Household
Tax Rate
$0 to $11,600
$0 to $11,600
$0 to $23,200
$0 to $16,550
10%
$11,601 to $47,150
$11,601 to $47,150
$23,201 to $94,300
$16,551 to $63,100
12%
$47,151 to $100,525
$47,151 to $100,525
$94,301 to $201,050
$63,101 to $100,500
22%
$100,526 to $191,950
$100,526 to $191,950
$201,051 to $383,900
$100,501 to $191,950
24%
$191,951 to $243,725
$191,951 to $243,725
$383,901 to $487,450
$191,951 to $243,700
32%
$243,726 to $609,350
$243,726 to $365,600
$487,451 to $731,200
$243,701 to $609,350
35%
$609,351 or more
$365,601 or more
$731,201 or more
$609,351 or more
37%
2024 Tax Season Standard Deductions
Single filer and married filing separately
Married filing jointly (includes qualifying widow/er)
Head of Household
$14,600
$29,200
$21,900
Retirement Saving Tips
It’s not too late to contribute to an IRA. Both the traditional and Roth IRAs allow you to make contributions for 2024 up until the tax-filing deadline of the following year – which this year is Tuesday, April 15. The advantage to this later deadline is that you can complete your taxes before they are due, then adjust them to reduce your tax liability if needed by contributing to your IRA. The total maximum contribution you can make to all of your IRAs combined (both Roths and traditional) is $7,000 for 2024 or $8,000 if you are 50 years or older.
However, if you have a Roth IRA, there are restrictions to contributions based on your 2024 income. You may make the maximum contribution to your Roth only if your 2024 modified adjusted gross income (MAGI) is less than a certain threshold.
Filing Status
MAGI
Contribution amount
Single and Head of Household filers
Below $146,000
Between $146,001 and 161,000
Above $161,000
$7,000/$8,000 (age 50+)
Phased (IRS Worksheet 2-2)
Nothing
Married filing jointly
(includes qualifying widow/er)
Below $230,000
Between $230,000 and $240,000
Above $240,000
$7,000/$8,000 (age 50+)
Phased (IRS Worksheet 2-2)
Nothing
Be aware that the amount of deduction you can claim for a traditional IRA contribution may be limited if you or your spouse are covered by a retirement plan at work.
Filing Status
MAGI
Deduction amount
Single and Head of Household filers
$77,000 or less
Between $77,000 and 87,000
$87,000 or more
Full deduction
Partial (IRS Worksheet 1-2)
None
Married filing jointly
(includes qualifying widow/er)
$123,000 or less
Between $123,000 and 143,000
$143,000 or more
Full deduction
Partial (IRS Worksheet 1-2)
None
Married filing separately
Less than $10,000
$10,000 or more
Partial (IRS Worksheet 1-2)
None
If you make a traditional and/or Roth IRA contribution by the April 15 deadline, you may qualify for the Retirement Saver’s Credit (also available if you contributed to an employer plan by Dec. 31, 2024). The maximum credit is $1,000 ($2,000 for married couples), and it can increase your refund or reduce the tax you owe. However, the saver’s credit is subject to other deductions, credits, and income restrictions.
Filing Status
MAGI
Single and Married filing separately
up to $57,375
Married couples filing jointly
(includes qualifying widow/er)
up to $76,500
Head of Household Filers
up to $57,375
Work with an experienced tax preparer to take advantage of legitimate deductions and credits to ensure that you only pay what is required for your situation.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The CAC Payback Period looks at how a business needs to recover its investment in attracting new customers. It is especially crucial for companies that are in industries with large marketing and sales costs. It’s an important metric because it helps businesses measure their performance in a number of ways.
First, it shows how well a business is managing its budget. Based on the resulting figure of the CAC Payback Period, the shorter the time required to break even on its customer acquisition costs, the more efficient a company is with its sales and marketing expenses. If, however, the result is high, this signals the company is doing something wrong and needs to analyze its current approach.
Running this analysis can also identify a company’s financial perils. The more prolonged the CAC Payback Period, the more likely a company might be facing cash flow concerns. Whether it is caused by overall economic conditions or industry or company-specific challenges, this is another reason for a company to run the numbers to see how it can mitigate or turn around the costs associated with acquiring customers.
The calculation also can help a business determine if it is able to expand to new products and markets and scale up existing product lines. The shorter the time needed to acquire new customers, the more likely a business can grow.
When investors and lenders analyze a company’s financials, including this metric, the more efficient a company is, and the more likely it will attract investors or have lenders offer favorable financing terms.
How to Calculate the CAC Payback Period
This scenario looks at $300,000 in customer acquisition costs, such as marketing, sales, etc., for a three-month period. The company obtained 1,000 new customers and is expected to gain $200,000 in new monthly recurring revenue (MRR), with an estimated gross margin of 60 percent.
First Step: Calculate the CAC by dividing Sales and Marketing Expenses by the new customers (1,000). It’s expressed as follows:
CAC = Sales and Marketing Expenses/Number of New Customers
CAC = $300,000/1,000 = $300 per customer
Second Step: This is to determine the monthly recurring revenue (MRR) per customer. The new MRR amount is divided by the number of newly acquired customers. It’s calculated as follows:
MRR = $200,000/1,000 = $200 per customer
Third Step: Determine the gross margin or how much remains from revenue after subtracting direct costs. In this case, we’ll use 60 percent.
Fourth (and Final) Step: This step determines how many months it will take to recoup the customer acquisition costs from the profits generated by the newly acquired customer. It’s calculated as follows:
CAC Payback Period = $300/($200 x 0.60) = 2.5
Based on the resulting 2.5 figure, it takes, on average, 2.5 months of profit from the newly acquired customers to pay for the customer’s acquisition cost.
Understanding CAC Payback Period Efficiency
If it’s less than 12 months, it’s favorable. This implies a business has an efficient approach to profitability and growth. However, it’s not a hard and fast rule because the repayment time frame can fluctuate based on the economy and the business operations. If a company is a low-margin business or industry (e-commerce, groceries, etc.), a far tighter payback time frame would be necessary to be viable.
There are many factors that can affect this company-specific measurement, such as the industry or sector, current economic conditions, or the business’ approach to gaining new customers. If a company has a shorter CAC Payback Period in an industry that has a generally accepted longer one, this can imply that the company is more efficient in its operations.
This metric is another tool in a financial analyst’s toolbox that can measure and identify efficiency (or lack thereof) and help put businesses back on track for greater financial health.
Calculating the CAC Payback Period
January 1, 2025 · Blog, General Business News
⏱ 4 min read
The CAC Payback Period looks at how a business needs to recover its investment in attracting new customers. It is especially crucial for companies that are in industries with large marketing and sales costs. It’s an important metric because it helps businesses measure their performance in a number of ways.
First, it shows how well a business is managing its budget. Based on the resulting figure of the CAC Payback Period, the shorter the time required to break even on its customer acquisition costs, the more efficient a company is with its sales and marketing expenses. If, however, the result is high, this signals the company is doing something wrong and needs to analyze its current approach.
Running this analysis can also identify a company’s financial perils. The more prolonged the CAC Payback Period, the more likely a company might be facing cash flow concerns. Whether it is caused by overall economic conditions or industry or company-specific challenges, this is another reason for a company to run the numbers to see how it can mitigate or turn around the costs associated with acquiring customers.
The calculation also can help a business determine if it is able to expand to new products and markets and scale up existing product lines. The shorter the time needed to acquire new customers, the more likely a business can grow.
When investors and lenders analyze a company’s financials, including this metric, the more efficient a company is, and the more likely it will attract investors or have lenders offer favorable financing terms.
How to Calculate the CAC Payback Period
This scenario looks at $300,000 in customer acquisition costs, such as marketing, sales, etc., for a three-month period. The company obtained 1,000 new customers and is expected to gain $200,000 in new monthly recurring revenue (MRR), with an estimated gross margin of 60 percent.
First Step: Calculate the CAC by dividing Sales and Marketing Expenses by the new customers (1,000). It’s expressed as follows:
CAC = Sales and Marketing Expenses/Number of New Customers
CAC = $300,000/1,000 = $300 per customer
Second Step: This is to determine the monthly recurring revenue (MRR) per customer. The new MRR amount is divided by the number of newly acquired customers. It’s calculated as follows:
MRR = $200,000/1,000 = $200 per customer
Third Step: Determine the gross margin or how much remains from revenue after subtracting direct costs. In this case, we’ll use 60 percent.
Fourth (and Final) Step: This step determines how many months it will take to recoup the customer acquisition costs from the profits generated by the newly acquired customer. It’s calculated as follows:
CAC Payback Period = $300/($200 x 0.60) = 2.5
Based on the resulting 2.5 figure, it takes, on average, 2.5 months of profit from the newly acquired customers to pay for the customer’s acquisition cost.
Understanding CAC Payback Period Efficiency
If it’s less than 12 months, it’s favorable. This implies a business has an efficient approach to profitability and growth. However, it’s not a hard and fast rule because the repayment time frame can fluctuate based on the economy and the business operations. If a company is a low-margin business or industry (e-commerce, groceries, etc.), a far tighter payback time frame would be necessary to be viable.
There are many factors that can affect this company-specific measurement, such as the industry or sector, current economic conditions, or the business’ approach to gaining new customers. If a company has a shorter CAC Payback Period in an industry that has a generally accepted longer one, this can imply that the company is more efficient in its operations.
This metric is another tool in a financial analyst’s toolbox that can measure and identify efficiency (or lack thereof) and help put businesses back on track for greater financial health.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
A Dec. 3 proposal from FASB’s Accounting Standards Update (ASU) might provide some flexibility for private businesses and select nonprofits. “Financial Instruments – Credit Losses (Topic 326)” looks at measuring credit losses for contract assets and accounts receivable for these entities.
When it comes to determining projected credit losses for current accounts receivables and current contract assets, businesses face immense resource needs and reporting requirements, including for assets acquired prior to the publication dates of financial statements.
With public comments being received through Jan. 17, 2025, industry professionals have reported that when it comes to gauging projected credit losses for current contract assets and current accounts receivable, there’s a massive undertaking and validation necessary for assets collected prior to financial statement issuance dates. Industry professionals argue that being able to factor in collections post-balance sheet date in calculating expected credit losses would reduce the complexity for preparers, whereas, for third parties, including investors and others who utilize financial statements, it would provide them with valuable data.
FASB proposed an amendment to ASC 326 207 to allow private companies and certain not-for-profit entities to employ a more flexible and efficient way to better gauge their projected credit losses for current contract assets and accounts receivable that originate from transaction accounts under ASC 606.
Working with the Private Company Council (PCC) to look at stakeholders’ concerns that estimating projected credit losses can be exorbitant and complicated for financial proceedings, FASB is soliciting comments on whether or not to expand the scope of entities included for ASU standards, along with different asset classes.
Current Criteria
According to ASC 326-20, when expected credit losses are estimated by entities, an entity must evaluate their ability to garner cash flows via the lens of contemporary economic circumstances, rational and documented projections, and past losses. Past losses may need to be fine-tuned to approximate project credit losses if past circumstances change from present conditions or from well-ground estimates and documented projections. Another consideration when formulating credit loss projections is that entities aren’t required to factor in collections obtained post-balance sheet date.
Proposed Additions
When it comes to the proposed additions, FASB speaks to a practical expedient and an accounting policy election. The practical expedient concerns an entity’s well-grounded, data-dependent projections. If an entity chooses the practical expedient, it would be able to factor in collection activity beyond the balance sheet date when projecting expected credit losses.
Practical Expedient
To formulate projections that are rational and based on verified accounting details, this so-called practical expedient can be chosen by the entity that assumes its present balance sheet conditions will last for the entire projection time frame. Choosing a practical expedient also implies that an entity’s accounting policy will factor in collection activity past its balance sheet date when gauging expected credit losses. Specifically, under 326-20-30-10C for the practical expedient, during the projection time frame, an entity will maintain the exact circumstances of the balance sheet throughout the rational and data-based projection period.
If a business, for example, has determined a particular client is facing monetary challenges, it would account for its client’s financial issues through projections of estimated expected credit losses for said client, even though it has not impacted the business’ historical loss experience or if the business is up to date as of the balance sheet date.
Accounting Policy Election
Per 326-20-30-10E, when a practical expedient from 326-20-30-10C through 30-10D is chosen by entities for their accounting policy election when projecting credit losses, it signals that the entity factors in collection activity after the balance sheet date, but prior to the date of financial statement issuance. If an entity uses one or both of the practical expedient and/or accounting policy elections, disclosure is mandatory.
Conclusion
Lastly, such advice would be administered on a forward-looking basis, and both of these entities (PCC and FASB) will make the ultimate findings and guidelines of the implementation dates once industry professionals’ comments are considered. However, entities will likely be able to utilize these guidelines sooner.
For eligible companies, these standards could provide greater flexibility and the ability to divert resources to more productive allocations.
How Reporting Might be Less Complex in 2025
January 1, 2025 · Accounting News, Blog
⏱ 4 min read
A Dec. 3 proposal from FASB’s Accounting Standards Update (ASU) might provide some flexibility for private businesses and select nonprofits. “Financial Instruments – Credit Losses (Topic 326)” looks at measuring credit losses for contract assets and accounts receivable for these entities.
When it comes to determining projected credit losses for current accounts receivables and current contract assets, businesses face immense resource needs and reporting requirements, including for assets acquired prior to the publication dates of financial statements.
With public comments being received through Jan. 17, 2025, industry professionals have reported that when it comes to gauging projected credit losses for current contract assets and current accounts receivable, there’s a massive undertaking and validation necessary for assets collected prior to financial statement issuance dates. Industry professionals argue that being able to factor in collections post-balance sheet date in calculating expected credit losses would reduce the complexity for preparers, whereas, for third parties, including investors and others who utilize financial statements, it would provide them with valuable data.
FASB proposed an amendment to ASC 326 207 to allow private companies and certain not-for-profit entities to employ a more flexible and efficient way to better gauge their projected credit losses for current contract assets and accounts receivable that originate from transaction accounts under ASC 606.
Working with the Private Company Council (PCC) to look at stakeholders’ concerns that estimating projected credit losses can be exorbitant and complicated for financial proceedings, FASB is soliciting comments on whether or not to expand the scope of entities included for ASU standards, along with different asset classes.
Current Criteria
According to ASC 326-20, when expected credit losses are estimated by entities, an entity must evaluate their ability to garner cash flows via the lens of contemporary economic circumstances, rational and documented projections, and past losses. Past losses may need to be fine-tuned to approximate project credit losses if past circumstances change from present conditions or from well-ground estimates and documented projections. Another consideration when formulating credit loss projections is that entities aren’t required to factor in collections obtained post-balance sheet date.
Proposed Additions
When it comes to the proposed additions, FASB speaks to a practical expedient and an accounting policy election. The practical expedient concerns an entity’s well-grounded, data-dependent projections. If an entity chooses the practical expedient, it would be able to factor in collection activity beyond the balance sheet date when projecting expected credit losses.
Practical Expedient
To formulate projections that are rational and based on verified accounting details, this so-called practical expedient can be chosen by the entity that assumes its present balance sheet conditions will last for the entire projection time frame. Choosing a practical expedient also implies that an entity’s accounting policy will factor in collection activity past its balance sheet date when gauging expected credit losses. Specifically, under 326-20-30-10C for the practical expedient, during the projection time frame, an entity will maintain the exact circumstances of the balance sheet throughout the rational and data-based projection period.
If a business, for example, has determined a particular client is facing monetary challenges, it would account for its client’s financial issues through projections of estimated expected credit losses for said client, even though it has not impacted the business’ historical loss experience or if the business is up to date as of the balance sheet date.
Accounting Policy Election
Per 326-20-30-10E, when a practical expedient from 326-20-30-10C through 30-10D is chosen by entities for their accounting policy election when projecting credit losses, it signals that the entity factors in collection activity after the balance sheet date, but prior to the date of financial statement issuance. If an entity uses one or both of the practical expedient and/or accounting policy elections, disclosure is mandatory.
Conclusion
Lastly, such advice would be administered on a forward-looking basis, and both of these entities (PCC and FASB) will make the ultimate findings and guidelines of the implementation dates once industry professionals’ comments are considered. However, entities will likely be able to utilize these guidelines sooner.
For eligible companies, these standards could provide greater flexibility and the ability to divert resources to more productive allocations.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Improving Federal Building Security Act of 2024 (S 3613) – The Federal Protective Service (FPS) contracts security guards to control access to government facilities and screen visitors to detect prohibited items, such as pepper spray and batons. Earlier this year, FPS investigators conducted a covert test at certain federal buildings in which the guards failed to detect prohibited items about 50 percent of the time. In response, Congress passed this bill requiring Facility Security Committees to respond to security recommendations issued by the FPS. It also mandates that the Homeland Security Department submit an unredacted report to Congress regarding FPS surveillance technology recommendations as well as summarize the FPS recommendations that buildings accepted or rejected. However, no additional funding for security is appropriated by the bill, which will sunset five years following enactment. The act was introduced on Jan. 18, 2024, by Sen. Gary Peters (D-MI). It passed in the Senate on March 23, the House on Dec. 10, and was signed into law on Dec. 17.
Servicemember Quality of Life Improvement and National Defense Authorization Act for Fiscal Year 2025 (HR 5009) – This year’s version of the annual funding bill features a 14.5 percent increase in pay for junior enlisted servicemembers, as well as a 4.5 percent pay raise for all other personnel. The legislation also provides cost-of-living allowances per location, improved housing/barracks repair programs, more access to medical and mental health services, and increased employment support for military spouses. The legislation was introduced by Rep. David Joyce (R-OH) on July 27, 2023. This is a bipartisan bill that has passed in both the Senate and the House with various changes. It is currently awaiting signature by the White House for enactment.
Coastal Habitat Conservation Act of 2023 (HR 2950) – Introduced by Rep. Jared Huffman (D-CA) on April 7, 2023, this bill passed the House on Sept. 24, 2024, the Senate on Nov. 21, and was signed into law on Dec. 11. The legislation empowers the Coastal Program of the United States Fish and Wildlife Service to increase efforts to assess, protect, restore and enhance key coastal environments that provide fish and wildlife habitats for certain federal trust species.
Thomas R. Carper Water Resources Development Act of 2024 (S 4367) – This legislation was introduced by Sen. Thomas Carper (D-DE) on May 20, 2024. It passed in the Senate on Aug. 1 and in the House (with changes) on Dec. 10; the final bill is expected to be approved and signed into law by the end of the congressional session. This bipartisan bill is designed to improve the nation’s water resources infrastructure, including ports and harbors, inland waterway navigation, and flood and storm protection; it also strengthens our resilience during natural disasters. The legislation also institutes reforms at the U.S. Army Corps of Engineers in order to streamline processes and deploy projects faster.
SHIELD Against CCP Act (HR 9668) – Introduced on Sept. 18, 2024, by Rep. Dale Strong (R-AL), this bill would establish a task force working with the Department of Homeland Security. The group’s sole focus would be on countering terrorism, cybersecurity, and border/port security related to threats posed by the Chinese Communist Party. The legislation is in response to recent CCP activities such as stealing intellectual property and technology, threats to economic supply chain security and critical infrastructure, and surveillance activities targeting U.S. defense sites and even American citizens. The bipartisan bill passed in the House on Dec. 10 and is currently in the Senate.
Increasing Baseline Updates Act (HR 9716) – In the first quarter of each year, the Congressional Budget Office provides Congress with an annual baseline 10-year projection of the budget and economy based on the fiscal impact of legislative proposals. Updates are released in Q2 and Q3 to reflect newly enacted laws and economic conditions. This bill would mandate that the executive branch provide critical data to the CBO by February 1 of each year to produce a more accurate annual budget baseline. The bill passed in the House on Dec. 11 and currently lies with the Senate. It was introduced by Rep. Blake Moore (R-UT) on Sept. 20, 2024.
National Security
January 1, 2025 · Blog, Congress at Work, News
⏱ 4 min read
Improving Federal Building Security Act of 2024 (S 3613) – The Federal Protective Service (FPS) contracts security guards to control access to government facilities and screen visitors to detect prohibited items, such as pepper spray and batons. Earlier this year, FPS investigators conducted a covert test at certain federal buildings in which the guards failed to detect prohibited items about 50 percent of the time. In response, Congress passed this bill requiring Facility Security Committees to respond to security recommendations issued by the FPS. It also mandates that the Homeland Security Department submit an unredacted report to Congress regarding FPS surveillance technology recommendations as well as summarize the FPS recommendations that buildings accepted or rejected. However, no additional funding for security is appropriated by the bill, which will sunset five years following enactment. The act was introduced on Jan. 18, 2024, by Sen. Gary Peters (D-MI). It passed in the Senate on March 23, the House on Dec. 10, and was signed into law on Dec. 17.
Servicemember Quality of Life Improvement and National Defense Authorization Act for Fiscal Year 2025 (HR 5009) – This year’s version of the annual funding bill features a 14.5 percent increase in pay for junior enlisted servicemembers, as well as a 4.5 percent pay raise for all other personnel. The legislation also provides cost-of-living allowances per location, improved housing/barracks repair programs, more access to medical and mental health services, and increased employment support for military spouses. The legislation was introduced by Rep. David Joyce (R-OH) on July 27, 2023. This is a bipartisan bill that has passed in both the Senate and the House with various changes. It is currently awaiting signature by the White House for enactment.
Coastal Habitat Conservation Act of 2023 (HR 2950) – Introduced by Rep. Jared Huffman (D-CA) on April 7, 2023, this bill passed the House on Sept. 24, 2024, the Senate on Nov. 21, and was signed into law on Dec. 11. The legislation empowers the Coastal Program of the United States Fish and Wildlife Service to increase efforts to assess, protect, restore and enhance key coastal environments that provide fish and wildlife habitats for certain federal trust species.
Thomas R. Carper Water Resources Development Act of 2024 (S 4367) – This legislation was introduced by Sen. Thomas Carper (D-DE) on May 20, 2024. It passed in the Senate on Aug. 1 and in the House (with changes) on Dec. 10; the final bill is expected to be approved and signed into law by the end of the congressional session. This bipartisan bill is designed to improve the nation’s water resources infrastructure, including ports and harbors, inland waterway navigation, and flood and storm protection; it also strengthens our resilience during natural disasters. The legislation also institutes reforms at the U.S. Army Corps of Engineers in order to streamline processes and deploy projects faster.
SHIELD Against CCP Act (HR 9668) – Introduced on Sept. 18, 2024, by Rep. Dale Strong (R-AL), this bill would establish a task force working with the Department of Homeland Security. The group’s sole focus would be on countering terrorism, cybersecurity, and border/port security related to threats posed by the Chinese Communist Party. The legislation is in response to recent CCP activities such as stealing intellectual property and technology, threats to economic supply chain security and critical infrastructure, and surveillance activities targeting U.S. defense sites and even American citizens. The bipartisan bill passed in the House on Dec. 10 and is currently in the Senate.
Increasing Baseline Updates Act (HR 9716) – In the first quarter of each year, the Congressional Budget Office provides Congress with an annual baseline 10-year projection of the budget and economy based on the fiscal impact of legislative proposals. Updates are released in Q2 and Q3 to reflect newly enacted laws and economic conditions. This bill would mandate that the executive branch provide critical data to the CBO by February 1 of each year to produce a more accurate annual budget baseline. The bill passed in the House on Dec. 11 and currently lies with the Senate. It was introduced by Rep. Blake Moore (R-UT) on Sept. 20, 2024.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The Social Security Fairness Act of 2023, formally known as H.R. 82, aimed at ending two provisions in the Social Security system that affect public sector employees who have earned pensions from jobs not covered by Social Security. These provisions are the Windfall Elimination Provision and the Government Pension Offset, both of which reduce or eliminate Social Security benefits for workers who have worked in both public-sector and private-sector jobs.
The Problem: WEP and GPO
The Windfall Elimination Provision and the Government Pension Offset were originally designed to prevent public sector workers from receiving larger Social Security benefits than they would have been entitled to had they worked in jobs covered by Social Security for their entire careers. However, critics argue that these provisions disproportionately harm workers who have spent a significant portion of their careers in public service, such as teachers, police officers, firefighters, and other state and local government employees.
Windfall Elimination Provision (WEP):
The WEP reduces the Social Security benefits of individuals who have worked in both the private sector (where they paid into Social Security) and the public sector (where they often did not contribute to Social Security). Typically, Social Security benefits are based on an individual’s 35 highest-earning years. The WEP alters the formula used to calculate benefits for individuals with fewer than 30 years of substantial earnings in Social Security-covered employment, leading to a lower Social Security benefit than they would otherwise be entitled to. For many, this results in a significant reduction in the monthly payment they would have received under the standard Social Security formula.
Government Pension Offset (GPO):
The GPO affects spouses and widows/widowers of Social Security beneficiaries. Under this provision, individuals who receive a government pension from work that was not covered by Social Security (such as state or local government employees) see a reduction in their spousal or survivor benefits from Social Security. The offset is calculated by reducing the spousal or survivor benefit by an amount equal to two-thirds of the government pension. This can leave many public employees with little to no spousal or survivor benefits despite their spouse having paid into Social Security.
What H.R. 82 Seeks to Accomplish
By eliminating both the WEP and GPO, the bill aims to ensure that public sector workers who have earned Social Security benefits through their work in the private sector are not penalized by reductions in those benefits. It also seeks to provide fairer treatment for the spouses and survivors of government employees who may otherwise see their Social Security benefits reduced or eliminated entirely.
The bill has garnered bipartisan support, as lawmakers from both sides of the aisle recognize the fairness of eliminating these provisions, which many see as an unjust penalty against those who have dedicated their careers to public service. H.R. 82, if passed, would provide much-needed relief to millions of retirees, many of who are struggling with the financial impacts of these provisions.
Conclusion:
The introduction of H.R. 82, the Social Security Fairness Act of 2023, marks a crucial point in the ongoing debate over Social Security benefits for public sector workers. By eliminating the Windfall Elimination Provision and the Government Pension Offset, the bill would restore fairness and equity for millions of public employees who have spent their careers in service to their communities. As this bill progresses, it will likely remain a significant issue in discussions surrounding Social Security reform and the treatment of public sector employees.
President Joe Biden signed H.R. 82, the Social Security Fairness Act, into law on Sunday, January 5, 2025, at 3:00 p.m. Central Time Zone.
The Social Security Fairness Act of 2023: More Retirement Income for Teachers, Police, Firefighters & Gov. Workers
January 1, 2025 · Blog, Guest Article of the Month
⏱ 3 min read
The Social Security Fairness Act of 2023, formally known as H.R. 82, aimed at ending two provisions in the Social Security system that affect public sector employees who have earned pensions from jobs not covered by Social Security. These provisions are the Windfall Elimination Provision and the Government Pension Offset, both of which reduce or eliminate Social Security benefits for workers who have worked in both public-sector and private-sector jobs.
The Problem: WEP and GPO
The Windfall Elimination Provision and the Government Pension Offset were originally designed to prevent public sector workers from receiving larger Social Security benefits than they would have been entitled to had they worked in jobs covered by Social Security for their entire careers. However, critics argue that these provisions disproportionately harm workers who have spent a significant portion of their careers in public service, such as teachers, police officers, firefighters, and other state and local government employees.
Windfall Elimination Provision (WEP):
The WEP reduces the Social Security benefits of individuals who have worked in both the private sector (where they paid into Social Security) and the public sector (where they often did not contribute to Social Security). Typically, Social Security benefits are based on an individual’s 35 highest-earning years. The WEP alters the formula used to calculate benefits for individuals with fewer than 30 years of substantial earnings in Social Security-covered employment, leading to a lower Social Security benefit than they would otherwise be entitled to. For many, this results in a significant reduction in the monthly payment they would have received under the standard Social Security formula.
Government Pension Offset (GPO):
The GPO affects spouses and widows/widowers of Social Security beneficiaries. Under this provision, individuals who receive a government pension from work that was not covered by Social Security (such as state or local government employees) see a reduction in their spousal or survivor benefits from Social Security. The offset is calculated by reducing the spousal or survivor benefit by an amount equal to two-thirds of the government pension. This can leave many public employees with little to no spousal or survivor benefits despite their spouse having paid into Social Security.
What H.R. 82 Seeks to Accomplish
By eliminating both the WEP and GPO, the bill aims to ensure that public sector workers who have earned Social Security benefits through their work in the private sector are not penalized by reductions in those benefits. It also seeks to provide fairer treatment for the spouses and survivors of government employees who may otherwise see their Social Security benefits reduced or eliminated entirely.
The bill has garnered bipartisan support, as lawmakers from both sides of the aisle recognize the fairness of eliminating these provisions, which many see as an unjust penalty against those who have dedicated their careers to public service. H.R. 82, if passed, would provide much-needed relief to millions of retirees, many of who are struggling with the financial impacts of these provisions.
Conclusion:
The introduction of H.R. 82, the Social Security Fairness Act of 2023, marks a crucial point in the ongoing debate over Social Security benefits for public sector workers. By eliminating the Windfall Elimination Provision and the Government Pension Offset, the bill would restore fairness and equity for millions of public employees who have spent their careers in service to their communities. As this bill progresses, it will likely remain a significant issue in discussions surrounding Social Security reform and the treatment of public sector employees.
President Joe Biden signed H.R. 82, the Social Security Fairness Act, into law on Sunday, January 5, 2025, at 3:00 p.m. Central Time Zone.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The Salt Typhoon cyberattack is among recent cyberattacks that reaffirm the urgent need for robust data security measures. This attack targeted major telecommunications providers, compromising critical infrastructure and potentially exposing vast amounts of sensitive data. With cyberthreats becoming more sophisticated, businesses and individuals must prioritize data security to maintain trust and compliance.
The Role of Apps in Managing and Protecting Client Data
Businesses need apps because they make the work easier and more organized. Apps help teams communicate better, manage tasks, and share information quickly, no matter where people are. The apps also simplify handling customer needs, improving service, and tracking business performance. Generally, apps save time while helping businesses work smarter and stay competitive.
One of the most critical uses of apps is managing client data. This data includes personal details like names and addresses. It also includes financial information such as bank details, as well as business-specific data like contracts and project plans. Losing or exposing this sensitive information can lead to severe consequences, including financial losses, legal penalties, and damaged reputations. Clients may lose trust in your business, leading to lost opportunities and reduced customer loyalty. By using apps effectively, businesses can better organize, safeguard, and utilize client data to build stronger relationships and maintain long-term success.
Encryption: A Critical Security Measure
Encryption has become crucial in modern data security. It transforms readable data into an unreadable format, ensuring only authorized parties can access the information. There are various types of encryptions, including end-to-end encryption (E2EE), which protects data during transmission, and at-rest encryption, which secures stored data.
Following the Salt Typhoon cyberattacks, the FBI and Cybersecurity and Infrastructure Security Agency (CISA) issued a joint advisory urging individuals and organizations to prioritize using encrypted communication channels. Given the vulnerability of traditional communication methods, the agencies strongly recommended adopting end-to-end encrypted messaging apps like Signal for secure communication. This recommendation aims to mitigate the risks associated with compromised telecommunication networks. It also helps protect sensitive information from unauthorized access. Even if cybercriminals intercept the data, they cannot decipher it without the encryption key. This layer of protection mitigates the risks of unauthorized access and data breaches, making encryption an essential tool for businesses.
The Role of Encrypted Apps
Enhanced security: Encrypted apps provide a critical layer of defense against sophisticated cyberattacks. By encrypting data both in transit and at rest, these apps ensure that even if communication networks are compromised, sensitive information remains inaccessible to attackers.
Compliance with regulations: With so many ongoing cyberattacks, regulatory scrutiny of data security practices has intensified. Encrypted apps can help businesses comply with relevant regulations, such as the GDPR and CCPA, by demonstrating a commitment to data protection.
Building trust and customer loyalty: Customers are increasingly wary of data breaches in an era of heightened cybersecurity concerns. Utilizing encrypted apps demonstrates a commitment to data security and privacy, fostering trust and loyalty among clients.
Protecting business operations: Encrypted apps are crucial for protecting client data and safeguarding critical business information, such as intellectual property, financial records, and internal communications. This ensures the continuity and integrity of business operations, even in the face of advanced cyber threats.
Choosing and Implementing Encrypted Apps
When selecting and implementing the right encrypted apps, it is important to consider them carefully. First, it is good to consider industry-specific needs as different industries have different data security needs. For example, while a healthcare provider must comply with Health Insurance Portability and Accountability Act (HIPAA) regulations, a business in the financial industry must adhere to banking regulations. This calls for selecting industry-specific apps.
Businesses also must prioritize apps with robust security features, such as strong encryption algorithms, multifactor authentication, and regular security updates. It is also important to carefully review the data privacy policies of app providers and ensure compliance with relevant regulations.
Effective employee training is also essential for successfully implementing encrypted apps. Employees must be educated on the importance of data security, the proper use of encrypted apps, and best practices for handling sensitive information.
Conclusion
Client data is one of a business’s most valuable assets, and protecting it is paramount. The growing threat of cyberattacks and the increasing complexity of data protection regulations make encryption an essential tool. By embracing encrypted communication channels, businesses can significantly enhance their resilience against sophisticated cyberattacks, protect sensitive client data, and maintain a competitive edge in today’s digital economy.
Securing Client Data: The Importance of Encrypted Apps
January 1, 2025 · Blog, News, What's New in Technology
⏱ 4 min read
The Salt Typhoon cyberattack is among recent cyberattacks that reaffirm the urgent need for robust data security measures. This attack targeted major telecommunications providers, compromising critical infrastructure and potentially exposing vast amounts of sensitive data. With cyberthreats becoming more sophisticated, businesses and individuals must prioritize data security to maintain trust and compliance.
The Role of Apps in Managing and Protecting Client Data
Businesses need apps because they make the work easier and more organized. Apps help teams communicate better, manage tasks, and share information quickly, no matter where people are. The apps also simplify handling customer needs, improving service, and tracking business performance. Generally, apps save time while helping businesses work smarter and stay competitive.
One of the most critical uses of apps is managing client data. This data includes personal details like names and addresses. It also includes financial information such as bank details, as well as business-specific data like contracts and project plans. Losing or exposing this sensitive information can lead to severe consequences, including financial losses, legal penalties, and damaged reputations. Clients may lose trust in your business, leading to lost opportunities and reduced customer loyalty. By using apps effectively, businesses can better organize, safeguard, and utilize client data to build stronger relationships and maintain long-term success.
Encryption: A Critical Security Measure
Encryption has become crucial in modern data security. It transforms readable data into an unreadable format, ensuring only authorized parties can access the information. There are various types of encryptions, including end-to-end encryption (E2EE), which protects data during transmission, and at-rest encryption, which secures stored data.
Following the Salt Typhoon cyberattacks, the FBI and Cybersecurity and Infrastructure Security Agency (CISA) issued a joint advisory urging individuals and organizations to prioritize using encrypted communication channels. Given the vulnerability of traditional communication methods, the agencies strongly recommended adopting end-to-end encrypted messaging apps like Signal for secure communication. This recommendation aims to mitigate the risks associated with compromised telecommunication networks. It also helps protect sensitive information from unauthorized access. Even if cybercriminals intercept the data, they cannot decipher it without the encryption key. This layer of protection mitigates the risks of unauthorized access and data breaches, making encryption an essential tool for businesses.
The Role of Encrypted Apps
Enhanced security: Encrypted apps provide a critical layer of defense against sophisticated cyberattacks. By encrypting data both in transit and at rest, these apps ensure that even if communication networks are compromised, sensitive information remains inaccessible to attackers.
Compliance with regulations: With so many ongoing cyberattacks, regulatory scrutiny of data security practices has intensified. Encrypted apps can help businesses comply with relevant regulations, such as the GDPR and CCPA, by demonstrating a commitment to data protection.
Building trust and customer loyalty: Customers are increasingly wary of data breaches in an era of heightened cybersecurity concerns. Utilizing encrypted apps demonstrates a commitment to data security and privacy, fostering trust and loyalty among clients.
Protecting business operations: Encrypted apps are crucial for protecting client data and safeguarding critical business information, such as intellectual property, financial records, and internal communications. This ensures the continuity and integrity of business operations, even in the face of advanced cyber threats.
Choosing and Implementing Encrypted Apps
When selecting and implementing the right encrypted apps, it is important to consider them carefully. First, it is good to consider industry-specific needs as different industries have different data security needs. For example, while a healthcare provider must comply with Health Insurance Portability and Accountability Act (HIPAA) regulations, a business in the financial industry must adhere to banking regulations. This calls for selecting industry-specific apps.
Businesses also must prioritize apps with robust security features, such as strong encryption algorithms, multifactor authentication, and regular security updates. It is also important to carefully review the data privacy policies of app providers and ensure compliance with relevant regulations.
Effective employee training is also essential for successfully implementing encrypted apps. Employees must be educated on the importance of data security, the proper use of encrypted apps, and best practices for handling sensitive information.
Conclusion
Client data is one of a business’s most valuable assets, and protecting it is paramount. The growing threat of cyberattacks and the increasing complexity of data protection regulations make encryption an essential tool. By embracing encrypted communication channels, businesses can significantly enhance their resilience against sophisticated cyberattacks, protect sensitive client data, and maintain a competitive edge in today’s digital economy.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Personal Income Tax Planning Strategies for Year-End 2024
As 2024 draws to a close, it’s the perfect time to review your personal income tax situation and implement strategies to minimize your tax liability for the year. Proactive year-end tax planning can lead to significant savings, as well as ensure that you take full advantage of tax credits, deductions and other opportunities available to you.
1. Maximize Contributions to Retirement Accounts
One of the most effective ways to reduce your taxable income is by contributing to tax-advantaged retirement accounts. In 2024, you may contribute up to $23,000 to a 401(k) or similar employer-sponsored plan, with an additional $7,500 catch-up contribution if you’re over age 50. These contributions are made pre-tax, meaning they reduce your taxable income for the year, potentially lowering your tax bill.
Similarly, if you’re eligible, consider contributing to an IRA. For 2024, the maximum contribution limit for a traditional IRA and/or Roth IRA is $7,000 ($8,000 if you’re 50 or older). Contributions to a traditional IRA may be tax-deductible depending on your income and whether you or your spouse are covered by an employer-sponsored retirement plan. If you’re not eligible for deductions due to income limits, consider a Roth IRA, where contributions are made after-tax, but qualified withdrawals in retirement are tax-free.
2. Take Advantage of Flexible Spending Accounts (FSAs) and Health Savings Accounts (HSAs)
If your employer offers a Flexible Spending Account (FSA), use the remainder of your FSA funds before they expire. FSAs allow you to put away pre-tax money to cover medical expenses, and the limit for 2024 is $3,200. Depending on your employer’s plan, unused funds may be forfeited after the year-end, although some plans may offer a grace period or carryover option for a small portion of the balance.
For those eligible for a Health Savings Account (HSA), contributing the maximum allowable amount can provide immediate tax savings. For 2024, the HSA contribution limit is $4,150 for individuals and $8,300 for families, with an additional $1,000 catch-up contribution for individuals age 55 or older.
3. Harvest Capital Losses
If you’ve realized capital gains in 2024, it may be beneficial to offset those gains with capital losses. Known as tax-loss harvesting, this strategy involves selling investments that have declined in value to realize losses, which can be used to offset your capital gains. If your capital losses exceed your gains, you can use the remaining losses to offset up to $3,000 of ordinary income ($1,500 if married and filing separately).
Make sure to consider the “wash sale” rule, which disallows a deduction if you buy the same or substantially identical security within 30 days of selling at a loss. This rule is meant to prevent taxpayers from selling assets for tax benefits and then repurchasing the same assets immediately.
4. Bunch Charitable Contributions
If you’re planning to make charitable donations, consider bunching your contributions into one year to exceed the standard deduction threshold. This strategy allows you to itemize deductions for one year by making larger charitable contributions in a single year while taking the standard deduction in the following year. The standard deduction for 2024 is $29,200 for married couples filing jointly and $14,600 for single filers, which means if your itemized deductions do not exceed these amounts, you may benefit from grouping two or more years’ worth of charitable donations into one year.
5. Review Your Tax Withholding
As the year ends, review your tax withholding to ensure you’re not over- or under-paying throughout the year. If you’ve had a major life change in 2024, such as marriage, divorce, a child or a new job, adjusting your withholding can prevent underpayment penalties or a large tax bill. You can use the IRS Tax Withholding Estimator tool to assess whether your withholding is on track or, if necessary, submit a new Form W-4 to adjust your withholding for the final paychecks of the year.
6. Plan for Estimated Taxes if Self-Employed
For self-employed individuals, it’s important to ensure you’ve made sufficient estimated tax payments throughout the year. If you expect to owe additional taxes for 2024, you may want to increase your final estimated payment by Jan. 15, 2025, to avoid penalties. You can calculate your estimated tax liability using Form 1040-ES.
Conclusion
Tax planning is an essential part of personal finance. With 2024 coming to an end, it’s the right time to review your finances and take advantage of available tax-saving opportunities. By maximizing retirement account contributions, considering tax-loss harvesting and utilizing other year-end strategies, you can minimize your tax burden and keep more of your hard-earned income. Be sure to consult with a tax professional to tailor these strategies to your unique financial situation and ensure you’re in the best possible position for the year ahead.
Tax Planning 2024
December 1, 2024 · Blog, Tax and Financial News
⏱ 4 min read
Personal Income Tax Planning Strategies for Year-End 2024
As 2024 draws to a close, it’s the perfect time to review your personal income tax situation and implement strategies to minimize your tax liability for the year. Proactive year-end tax planning can lead to significant savings, as well as ensure that you take full advantage of tax credits, deductions and other opportunities available to you.
1. Maximize Contributions to Retirement Accounts
One of the most effective ways to reduce your taxable income is by contributing to tax-advantaged retirement accounts. In 2024, you may contribute up to $23,000 to a 401(k) or similar employer-sponsored plan, with an additional $7,500 catch-up contribution if you’re over age 50. These contributions are made pre-tax, meaning they reduce your taxable income for the year, potentially lowering your tax bill.
Similarly, if you’re eligible, consider contributing to an IRA. For 2024, the maximum contribution limit for a traditional IRA and/or Roth IRA is $7,000 ($8,000 if you’re 50 or older). Contributions to a traditional IRA may be tax-deductible depending on your income and whether you or your spouse are covered by an employer-sponsored retirement plan. If you’re not eligible for deductions due to income limits, consider a Roth IRA, where contributions are made after-tax, but qualified withdrawals in retirement are tax-free.
2. Take Advantage of Flexible Spending Accounts (FSAs) and Health Savings Accounts (HSAs)
If your employer offers a Flexible Spending Account (FSA), use the remainder of your FSA funds before they expire. FSAs allow you to put away pre-tax money to cover medical expenses, and the limit for 2024 is $3,200. Depending on your employer’s plan, unused funds may be forfeited after the year-end, although some plans may offer a grace period or carryover option for a small portion of the balance.
For those eligible for a Health Savings Account (HSA), contributing the maximum allowable amount can provide immediate tax savings. For 2024, the HSA contribution limit is $4,150 for individuals and $8,300 for families, with an additional $1,000 catch-up contribution for individuals age 55 or older.
3. Harvest Capital Losses
If you’ve realized capital gains in 2024, it may be beneficial to offset those gains with capital losses. Known as tax-loss harvesting, this strategy involves selling investments that have declined in value to realize losses, which can be used to offset your capital gains. If your capital losses exceed your gains, you can use the remaining losses to offset up to $3,000 of ordinary income ($1,500 if married and filing separately).
Make sure to consider the “wash sale” rule, which disallows a deduction if you buy the same or substantially identical security within 30 days of selling at a loss. This rule is meant to prevent taxpayers from selling assets for tax benefits and then repurchasing the same assets immediately.
4. Bunch Charitable Contributions
If you’re planning to make charitable donations, consider bunching your contributions into one year to exceed the standard deduction threshold. This strategy allows you to itemize deductions for one year by making larger charitable contributions in a single year while taking the standard deduction in the following year. The standard deduction for 2024 is $29,200 for married couples filing jointly and $14,600 for single filers, which means if your itemized deductions do not exceed these amounts, you may benefit from grouping two or more years’ worth of charitable donations into one year.
5. Review Your Tax Withholding
As the year ends, review your tax withholding to ensure you’re not over- or under-paying throughout the year. If you’ve had a major life change in 2024, such as marriage, divorce, a child or a new job, adjusting your withholding can prevent underpayment penalties or a large tax bill. You can use the IRS Tax Withholding Estimator tool to assess whether your withholding is on track or, if necessary, submit a new Form W-4 to adjust your withholding for the final paychecks of the year.
6. Plan for Estimated Taxes if Self-Employed
For self-employed individuals, it’s important to ensure you’ve made sufficient estimated tax payments throughout the year. If you expect to owe additional taxes for 2024, you may want to increase your final estimated payment by Jan. 15, 2025, to avoid penalties. You can calculate your estimated tax liability using Form 1040-ES.
Conclusion
Tax planning is an essential part of personal finance. With 2024 coming to an end, it’s the right time to review your finances and take advantage of available tax-saving opportunities. By maximizing retirement account contributions, considering tax-loss harvesting and utilizing other year-end strategies, you can minimize your tax burden and keep more of your hard-earned income. Be sure to consult with a tax professional to tailor these strategies to your unique financial situation and ensure you’re in the best possible position for the year ahead.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
What do you consider to be your purpose in this world? Few people think about their life that way. In Japan, they call it your ikigai. In France, they refer to your raison d’etre. For Americans, that roughly translates to your purpose in life or your reason for being.
It’s easy to consider your family or even your career as your reason to live. But true embracement of the ikigai concept is more of a lifestyle, not a specific person, place or thing.
Your purpose may not even be something you’ve pursued in your adult life. Many of us follow the socially expected path: higher education, a good job, a rewarding career, marriage, home, and family. But those things are not everyone’s raison d’etre. They might wake up one morning thinking that once they’ve achieved all those goals, they will finally get the chance to do the one they’ve always wanted. What is that?
The older we get, the more we lose a spouse or life partner, siblings, or children – and those who retire no longer have work to feel fulfilled. As part of your retirement planning effort, consider life without any of those things. How would you bear it? If you outlive your career and loved ones, what would you do?
Note that your ikigai does not insulate you from bad things happening. Instead, it’s the thing you look forward to when the smoke clears: the light at the end of the tunnel. On balance, it’s the thing that helps get you through the pain and restores happiness. In fact, discovering your raison d’etre can help you better cope with stress and loss. People who pursue their ikigai tend to have better mental health, experience fewer chronic diseases, and are more likely to live longer.
Oftentimes ikigai is felt as part of a process. For example, the joy of mixing ingredients to prepare baked goods or a meal. Planting a garden. Rebuilding an engine. It can be the process of writing or painting or playing an instrument, but not necessarily finishing a novel or singing in public. It can be as simple as finding joy in daily activities, nurturing relationships or doing community service.
Another advantage to ikigai is that it can connect you with other people who share your passion, which can be very important as you grow older and more isolated. By leaning into your ikigai, you could expand your social network with connections that are meaningful and fulfilling.
For some people, their raison d’etre is spiritual. A belief and perhaps a greater connection to a higher being. They may wish to spend more time becoming involved in church activities, reading scripture that supports their religion, or even exploring other religions.
The Japanese culture believes that each individual has an inherent ikigai based on their personal values and beliefs. One way to think about it is as your philosophy on life. Since this step is a part of retirement planning, it is fortunate that you have lived long enough to have developed some philosophies on life.
For example, some people discover that family does not just consist of blood relatives. Instead, their concept of family is people who are there through good and bad times, who always show love and respect, who you can rely on. Those things might not always be true among family members who meet the traditional definition. This type of ikigai may help you recognize that the death of loved ones does not necessarily mean you lose your family. You can always build and add to your family (e.g., neighbors and friends, fostering children or pets, big brother/big sister programs).
How Do You Find Your Ikigai??
Many times, the hustle and bustle of life keeps us from finding our true purpose. We proceed as loyal soldiers down a path prescribed by society instead of pursuing things that may bring us greater happiness. There’s nothing wrong with a career and family, but there is likely something more that each of us can pursue that is personal and soul-enriching. Sometimes, you can discover your raison d’etre by exploring your passions, values, strengths, and skills. For example, ask yourself the following questions:
When I was a child, I loved doing…
If money didn’t matter, I would be…
If I believed I could not fail, I would…
I completely lose track of time when I am…
I am most happy with who I am when I…
I am really good at…
If I didn’t care what others thought, I would…
In my free time, I love to…
If I had only six months to live, I would spend my time…
If I were to die tomorrow, I would regret that I did not…
Consider hobbies or classes that you’ve always wanted to try or past experiences or achievements that gave you a sense of satisfaction and fulfillment. Recall where you have found inspiration in the past, and pinpoint what lies at the cross-section of doing what you love and doing what you’re good at.
Remember that your reason for living is more of a journey, not a destination. Finding your ikigai may take a lifetime to discover, so don’t be afraid to try out different pursuits. In fact, your reason for being may simply be to try new things.
Pre-Retirement Planning Guide – Finding Purpose In Life
December 1, 2024 · Blog, Financial Planning
⏱ 5 min read
Step 7: Find Your Raison d’Etre
What do you consider to be your purpose in this world? Few people think about their life that way. In Japan, they call it your ikigai. In France, they refer to your raison d’etre. For Americans, that roughly translates to your purpose in life or your reason for being.
It’s easy to consider your family or even your career as your reason to live. But true embracement of the ikigai concept is more of a lifestyle, not a specific person, place or thing.
Your purpose may not even be something you’ve pursued in your adult life. Many of us follow the socially expected path: higher education, a good job, a rewarding career, marriage, home, and family. But those things are not everyone’s raison d’etre. They might wake up one morning thinking that once they’ve achieved all those goals, they will finally get the chance to do the one they’ve always wanted. What is that?
The older we get, the more we lose a spouse or life partner, siblings, or children – and those who retire no longer have work to feel fulfilled. As part of your retirement planning effort, consider life without any of those things. How would you bear it? If you outlive your career and loved ones, what would you do?
Note that your ikigai does not insulate you from bad things happening. Instead, it’s the thing you look forward to when the smoke clears: the light at the end of the tunnel. On balance, it’s the thing that helps get you through the pain and restores happiness. In fact, discovering your raison d’etre can help you better cope with stress and loss. People who pursue their ikigai tend to have better mental health, experience fewer chronic diseases, and are more likely to live longer.
Oftentimes ikigai is felt as part of a process. For example, the joy of mixing ingredients to prepare baked goods or a meal. Planting a garden. Rebuilding an engine. It can be the process of writing or painting or playing an instrument, but not necessarily finishing a novel or singing in public. It can be as simple as finding joy in daily activities, nurturing relationships or doing community service.
Another advantage to ikigai is that it can connect you with other people who share your passion, which can be very important as you grow older and more isolated. By leaning into your ikigai, you could expand your social network with connections that are meaningful and fulfilling.
For some people, their raison d’etre is spiritual. A belief and perhaps a greater connection to a higher being. They may wish to spend more time becoming involved in church activities, reading scripture that supports their religion, or even exploring other religions.
The Japanese culture believes that each individual has an inherent ikigai based on their personal values and beliefs. One way to think about it is as your philosophy on life. Since this step is a part of retirement planning, it is fortunate that you have lived long enough to have developed some philosophies on life.
For example, some people discover that family does not just consist of blood relatives. Instead, their concept of family is people who are there through good and bad times, who always show love and respect, who you can rely on. Those things might not always be true among family members who meet the traditional definition. This type of ikigai may help you recognize that the death of loved ones does not necessarily mean you lose your family. You can always build and add to your family (e.g., neighbors and friends, fostering children or pets, big brother/big sister programs).
How Do You Find Your Ikigai??
Many times, the hustle and bustle of life keeps us from finding our true purpose. We proceed as loyal soldiers down a path prescribed by society instead of pursuing things that may bring us greater happiness. There’s nothing wrong with a career and family, but there is likely something more that each of us can pursue that is personal and soul-enriching. Sometimes, you can discover your raison d’etre by exploring your passions, values, strengths, and skills. For example, ask yourself the following questions:
When I was a child, I loved doing…
If money didn’t matter, I would be…
If I believed I could not fail, I would…
I completely lose track of time when I am…
I am most happy with who I am when I…
I am really good at…
If I didn’t care what others thought, I would…
In my free time, I love to…
If I had only six months to live, I would spend my time…
If I were to die tomorrow, I would regret that I did not…
Consider hobbies or classes that you’ve always wanted to try or past experiences or achievements that gave you a sense of satisfaction and fulfillment. Recall where you have found inspiration in the past, and pinpoint what lies at the cross-section of doing what you love and doing what you’re good at.
Remember that your reason for living is more of a journey, not a destination. Finding your ikigai may take a lifetime to discover, so don’t be afraid to try out different pursuits. In fact, your reason for being may simply be to try new things.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Yep, it’s the end of another year! Chances are, you didn’t keep every resolution you made last year, for example, those goals about working out. (No shame here; we all do this!) However, the good news is that your fiscal goals can be a bit easier to achieve. Here are a few financial resolutions that are no-brainers, simple, and, best of all, no sweat.
Get a snapshot of your net worth. This is critical. Sit down and calculate this. When you know how much you have in terms of assets and liabilities, you can more easily determine where you need to make changes to your budget. For instance, this might be spending less on dining out and stocking more away in savings and investments. Understanding how much you have to work with is the first step to reaching your goals.
Pay off credit cards. This might well be an ongoing task, but the end of the year is a great time to take a breath, make a plan, and hit the ground running in the new year. If you have high-interest cards, look for limited-time, lower-interest and/or zero-interest cards. Some lenders will even give you as long as 21 months without interest. If you find yourself using credit cards more than you like, another way to get a handle on this is to use cash when you’re out at stores and restaurants. Seeing the dollars actually leaving your hands as opposed to just swiping your plastic might give you a needed dose of reality.
Update your savings goals. If you want to easily increase your savings, choose an amount and have it auto-drafted from your paycheck or checking account into your savings every month. This way, you’ll learn to live on the amount you have left. When you never see the amount you’re tucking away, you won’t miss it.
Review and reset your investments. Take some time to pull together all your assets: IRAs, retirement accounts, and employer 401(k) plans. If you can contribute more to any of these, all the better. For 401(k)s, the IRS just announced a cost-of-living adjustment for retirement plans and IRAs – the 401(k) contribution limit for 2025 is $23,500, up from $23,000 in 2024. However, individual retirement account (IRA) contributions will continue to be $7,000 in 2025, the same as in 2024. If you’re over 50, here’s some good news: You’ll be able to make even larger catch-up contributions than other workers because of a provision in Secure 2.0, a federal retirement law. Beginning in 2025, employees aged 60, 61, 62, or 63 who participate in workplace retirement plans can make catch-up contributions of up to $11,250.
Take a look at your credit report. This is key. You’re entitled to one free credit report a year from each of the three credit agencies, so doing this is easy peasy. Pull up your report and give it a look-see. If you see anything negative, take action to repair it. If there are any errors, correct them asap. To get started, go to AnnualCreditReport.com.
While there are many other money-related resolutions you can make, starting with ones that take minimal effort while yielding maximum results is a good place to begin, not to mention, a great way ease into the new year.
5 New Year’s Financial Resolutions You Can Actually Keep
December 1, 2024 · Blog, Tip of the Month
⏱ 3 min read
Yep, it’s the end of another year! Chances are, you didn’t keep every resolution you made last year, for example, those goals about working out. (No shame here; we all do this!) However, the good news is that your fiscal goals can be a bit easier to achieve. Here are a few financial resolutions that are no-brainers, simple, and, best of all, no sweat.
Get a snapshot of your net worth. This is critical. Sit down and calculate this. When you know how much you have in terms of assets and liabilities, you can more easily determine where you need to make changes to your budget. For instance, this might be spending less on dining out and stocking more away in savings and investments. Understanding how much you have to work with is the first step to reaching your goals.
Pay off credit cards. This might well be an ongoing task, but the end of the year is a great time to take a breath, make a plan, and hit the ground running in the new year. If you have high-interest cards, look for limited-time, lower-interest and/or zero-interest cards. Some lenders will even give you as long as 21 months without interest. If you find yourself using credit cards more than you like, another way to get a handle on this is to use cash when you’re out at stores and restaurants. Seeing the dollars actually leaving your hands as opposed to just swiping your plastic might give you a needed dose of reality.
Update your savings goals. If you want to easily increase your savings, choose an amount and have it auto-drafted from your paycheck or checking account into your savings every month. This way, you’ll learn to live on the amount you have left. When you never see the amount you’re tucking away, you won’t miss it.
Review and reset your investments. Take some time to pull together all your assets: IRAs, retirement accounts, and employer 401(k) plans. If you can contribute more to any of these, all the better. For 401(k)s, the IRS just announced a cost-of-living adjustment for retirement plans and IRAs – the 401(k) contribution limit for 2025 is $23,500, up from $23,000 in 2024. However, individual retirement account (IRA) contributions will continue to be $7,000 in 2025, the same as in 2024. If you’re over 50, here’s some good news: You’ll be able to make even larger catch-up contributions than other workers because of a provision in Secure 2.0, a federal retirement law. Beginning in 2025, employees aged 60, 61, 62, or 63 who participate in workplace retirement plans can make catch-up contributions of up to $11,250.
Take a look at your credit report. This is key. You’re entitled to one free credit report a year from each of the three credit agencies, so doing this is easy peasy. Pull up your report and give it a look-see. If you see anything negative, take action to repair it. If there are any errors, correct them asap. To get started, go to AnnualCreditReport.com.
While there are many other money-related resolutions you can make, starting with ones that take minimal effort while yielding maximum results is a good place to begin, not to mention, a great way ease into the new year.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
No matter the type of business or industry, being able to analyze and deduce patterns is essential to discovering a business’ financial health. Here are four commonly used calculations to help internal and external stakeholders determine an organization’s ability to manage its finances.
Break-Even Analysis
This formula analyzes fixed costs versus the profitability a business earns for every extra item it creates and sells.
Businesses that have smaller thresholds to meet their fixed costs to realize profitability have an easier break-even point to meet and exceed. Once the fixed costs threshold is satisfied and sales revenue outpaces variable costs, a business will know when it hits the break-even point.
Break Even Point (BEP) = Total Fixed Costs/(Price Per Unit – Variable Cost Per Unit)
This takes the total fixed costs divided by the price per individual unit minus each unit’s variable cost.
Examples of fixed costs are rent, taxes, insurance and wages. Examples of variable costs are raw materials, production supplies, utilities and packaging.
Another way to determine a company’s break-even point is as follows:
Contribution Margin = Item Price – Variable Cost Per Unit
This is illustrated by: $55 = ($85 – $30)
The item’s priced at $85, with a variable cost of $30, the contribution margin is $55 of how much revenue a company earns to pay for the remaining fixed costs.
Cash Ratio Formula
The cash ratio formula offers one way to look at a company’s liquidity position by comparing a company’s cash and cash equivalents to its current liabilities or debts due within the next 12 months. It shows how well positioned a business is (or is not) able to pay debts due within 12 months, and to satisfy the near-term obligations of its long-term debt.
It’s an important ratio that lenders look at when evaluating a company’s loan application. Instead of including assets such as accounts receivables, it factors in a business’ ability to take care of its financial obligations. It’s thought of as being a more real world look at how financially stable a business is.
This is defined as all income minus the cost of goods sold (COGS). COGS is comprised of expenses attributable to the creation of products, which include input materials and salaries for workers to produce such goods. However, it excludes expenses for taxes, overhead, debt, asset acquisitions, etc., among others. Another way to explain this calculation is to ask how much a business retains as profit once production costs are accounted for.
It’s calculated as follows: Gross Profit Margin = [(Net Sales – Cost of Goods Sold)/(New Sales)] x 100
Debt-to-Equity (D/E) Ratio
This is used to determine how much debt or financial leverage a company has on its books. It tells internal stakeholders and external parties what percentage of debt a company is using to operate compared to the business’ available operating reserves. This ratio contrasts a business’ complete financial obligations against its shareholder equity. Its primary use is to see how extensively it uses debt to operate.
It’s calculated as follows: Debt/Equity Ratio = Total Liabilities/Total Shareholders’ Equity.
While these calculations may seem straightforward, these are only a few examples of how businesses can calculate and analyze a company’s position – be it the owner, an employee or an outside lender or investor.
Common Business Accounting Calculations
December 1, 2024 · Blog, General Business News
⏱ 3 min read
No matter the type of business or industry, being able to analyze and deduce patterns is essential to discovering a business’ financial health. Here are four commonly used calculations to help internal and external stakeholders determine an organization’s ability to manage its finances.
Break-Even Analysis
This formula analyzes fixed costs versus the profitability a business earns for every extra item it creates and sells.
Businesses that have smaller thresholds to meet their fixed costs to realize profitability have an easier break-even point to meet and exceed. Once the fixed costs threshold is satisfied and sales revenue outpaces variable costs, a business will know when it hits the break-even point.
Break Even Point (BEP) = Total Fixed Costs/(Price Per Unit – Variable Cost Per Unit)
This takes the total fixed costs divided by the price per individual unit minus each unit’s variable cost.
Examples of fixed costs are rent, taxes, insurance and wages. Examples of variable costs are raw materials, production supplies, utilities and packaging.
Another way to determine a company’s break-even point is as follows:
Contribution Margin = Item Price – Variable Cost Per Unit
This is illustrated by: $55 = ($85 – $30)
The item’s priced at $85, with a variable cost of $30, the contribution margin is $55 of how much revenue a company earns to pay for the remaining fixed costs.
Cash Ratio Formula
The cash ratio formula offers one way to look at a company’s liquidity position by comparing a company’s cash and cash equivalents to its current liabilities or debts due within the next 12 months. It shows how well positioned a business is (or is not) able to pay debts due within 12 months, and to satisfy the near-term obligations of its long-term debt.
It’s an important ratio that lenders look at when evaluating a company’s loan application. Instead of including assets such as accounts receivables, it factors in a business’ ability to take care of its financial obligations. It’s thought of as being a more real world look at how financially stable a business is.
This is defined as all income minus the cost of goods sold (COGS). COGS is comprised of expenses attributable to the creation of products, which include input materials and salaries for workers to produce such goods. However, it excludes expenses for taxes, overhead, debt, asset acquisitions, etc., among others. Another way to explain this calculation is to ask how much a business retains as profit once production costs are accounted for.
It’s calculated as follows: Gross Profit Margin = [(Net Sales – Cost of Goods Sold)/(New Sales)] x 100
Debt-to-Equity (D/E) Ratio
This is used to determine how much debt or financial leverage a company has on its books. It tells internal stakeholders and external parties what percentage of debt a company is using to operate compared to the business’ available operating reserves. This ratio contrasts a business’ complete financial obligations against its shareholder equity. Its primary use is to see how extensively it uses debt to operate.
It’s calculated as follows: Debt/Equity Ratio = Total Liabilities/Total Shareholders’ Equity.
While these calculations may seem straightforward, these are only a few examples of how businesses can calculate and analyze a company’s position – be it the owner, an employee or an outside lender or investor.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
 Whether you file your income tax return early or at the last minute, there are ways to simplify the process and reduce what you owe – or even increase your refund – before the deadline.



 The CAC Payback Period looks at how a business needs to recover its investment in attracting new customers. It is especially crucial for companies that are in industries with large marketing and sales costs. It’s an important metric because it helps businesses measure their performance in a number of ways.
 A Dec. 3 proposal from FASB’s Accounting Standards Update (ASU) might provide some flexibility for private businesses and select nonprofits. “Financial Instruments – Credit Losses (Topic 326)” looks at measuring credit losses for contract assets and accounts receivable for these entities.
 Improving Federal Building Security Act of 2024 (S 3613) – The Federal Protective Service (FPS) contracts security guards to control access to government facilities and screen visitors to detect prohibited items, such as pepper spray and batons. Earlier this year, FPS investigators conducted a covert test at certain federal buildings in which the guards failed to detect prohibited items about 50 percent of the time. In response, Congress passed this bill requiring Facility Security Committees to respond to security recommendations issued by the FPS. It also mandates that the Homeland Security Department submit an unredacted report to Congress regarding FPS surveillance technology recommendations as well as summarize the FPS recommendations that buildings accepted or rejected. However, no additional funding for security is appropriated by the bill, which will sunset five years following enactment. The act was introduced on Jan. 18, 2024, by Sen. Gary Peters (D-MI). It passed in the Senate on March 23, the House on Dec. 10, and was signed into law on Dec. 17.
 The Social Security Fairness Act of 2023, formally known as H.R. 82, aimed at ending two provisions in the Social Security system that affect public sector employees who have earned pensions from jobs not covered by Social Security. These provisions are the Windfall Elimination Provision and the Government Pension Offset, both of which reduce or eliminate Social Security benefits for workers who have worked in both public-sector and private-sector jobs.
 The
 Personal Income Tax Planning Strategies for Year-End 2024
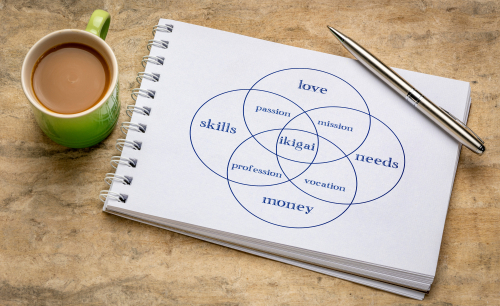 Step 7: Find Your Raison d’Etre
 Yep, it’s the end of another year! Chances are, you didn’t keep every resolution you made last year, for example, those goals about working out. (No shame here; we all do this!) However, the good news is that your fiscal goals can be a bit easier to achieve. Here are a few financial resolutions that are no-brainers, simple, and, best of all, no sweat.
 No matter the type of business or industry, being able to analyze and deduce patterns is essential to discovering a business’ financial health. Here are four commonly used calculations to help internal and external stakeholders determine an organization’s ability to manage its finances.